Buying a home is one of the biggest financial decisions many people make. Choosing the right mortgage lender can influence how much you pay in interest, what fees you incur, how quickly your loan closes, and which financing options are available to you.
The best mortgage lenders in 2026 offer a combination of competitive pricing, suitable loan products, clear application processes, and reliable customer support. Some lenders specialize in first-time homebuyers, while others focus on refinancing, government-backed mortgages, or borrowers purchasing higher-priced properties.
However, no single lender is the best choice for everyone. Your credit profile, income, down payment, location, and financial goals all influence which mortgage offer makes the most sense.
This guide compares leading U.S. mortgage lenders, explains their potential strengths, and shows you how to evaluate home loan offers before applying.
Best Mortgage Lenders in 2026: Quick Comparison
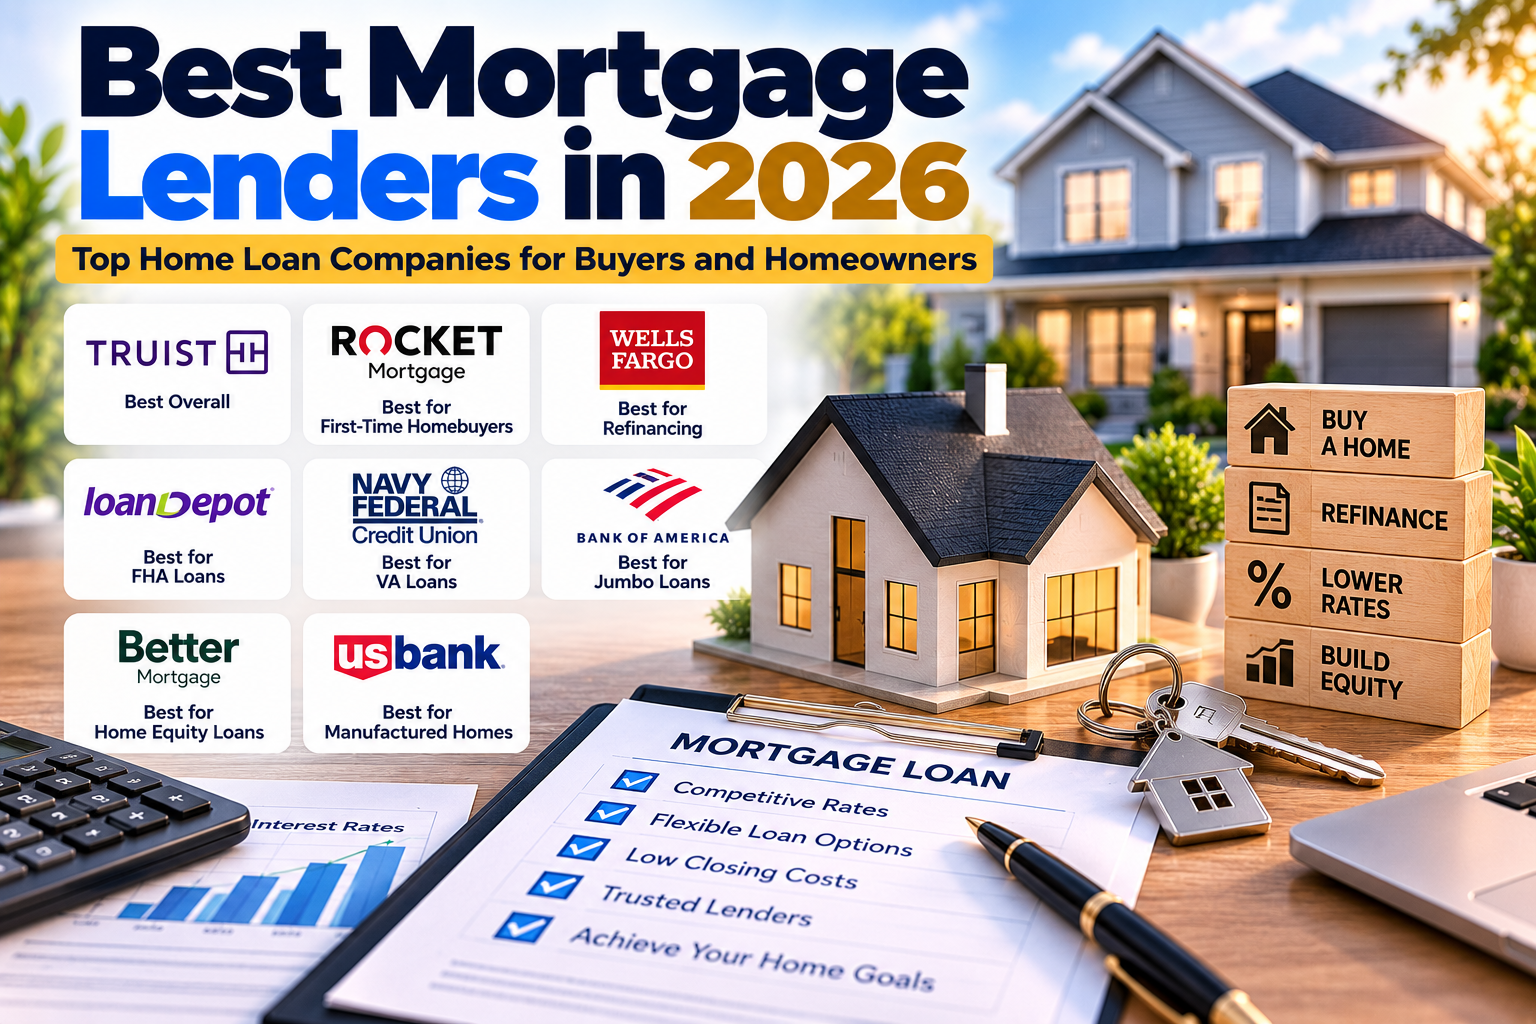
The following lenders are worth considering for different home financing needs. These categories are based on published 2026 mortgage reviews and award selections, not a guarantee of the lowest available rate for every borrower. <Cite refs={["turn368999search1","turn705376view0"]}/>
Mortgage lender | Best for | Key consideration |
|---|---|---|
Truist | Overall mortgage options | Compare its rates and fees with other lenders |
Rocket Mortgage | First-time homebuyers | Convenient digital application experience |
Wells Fargo | Cash-out refinancing | Review refinance costs and eligibility |
loanDepot | FHA loans | Check mortgage insurance and closing costs |
Navy Federal Credit Union | Eligible military borrowers | Membership and VA loan eligibility rules apply |
Bank of America | Jumbo mortgages | Credit and down payment requirements may be higher |
Better Mortgage | Home equity loans | Check available products and borrowing terms |
U.S. Bank | Manufactured home financing | Confirm property and loan eligibility |
Source: NerdWallet's 2026 mortgage lender awards and published lender comparisons. <Cite refs={["turn368999search1","turn705376view0"]}/>
1. Truist: Best Overall Mortgage Lender
<Entity category="company" value="Truist" disambig="US banking and mortgage lender"/> is a major U.S. financial institution offering mortgage products for different homebuying and refinancing needs.
NerdWallet selected Truist as its overall best mortgage lender for 2026, citing its pricing, range of loan products, application experience, and closing process. It also recognized the lender for refinancing and home equity lines of credit. <Cite refs={["turn368999search1","turn705376view0"]}/>
Why consider Truist?
Offers multiple mortgage and refinancing options.
Provides a digital application and rate-comparison experience.
May suit borrowers seeking a large lender with a broad product range.
Offers home equity financing for eligible homeowners.
What to consider
Your actual interest rate and fees depend on your application and loan details. Check property eligibility, available terms, closing costs, and any conditions attached to advertised offers.
Best for: Borrowers who want to compare a range of mortgage products from an established lender.
Official website: Truist
2. Rocket Mortgage: Best for First-Time Homebuyers
<Entity category="company" value="Rocket Mortgage" disambig="US online mortgage lender"/> is known for its online mortgage application process and digital tools that help borrowers move through home financing.
NerdWallet named Rocket Mortgage its best mortgage lender for first-time homebuyers in 2026. Its review highlighted the lender's digital experience and homebuying programs, including an option advertised with a 1% down payment for eligible borrowers. <Cite refs={["turn368999search1","turn705376view0"]}/>
Why consider Rocket Mortgage?
Online application and document submission.
Digital tools for checking application progress.
Mortgage options for eligible first-time buyers.
Access to loan specialists and application support.
What to consider
A low-down-payment program may have specific eligibility requirements, income restrictions, or other conditions. A small down payment also means borrowing a larger percentage of the home's purchase price.
Compare the APR, mortgage insurance, lender fees, and total cash required at closing before deciding.
Best for: First-time homebuyers who prefer a digital application experience.
Official website: Rocket Mortgage
3. Wells Fargo: Best for Cash-Out Refinancing
<Entity category="company" value="Wells Fargo" disambig="US bank and mortgage lender"/> offers home financing products, including mortgage refinancing for eligible borrowers.
Cash-out refinancing replaces an existing mortgage with a new, larger mortgage. The borrower receives the difference in cash after the existing mortgage and applicable costs are paid. This may provide funds for eligible expenses, but it also increases or restructures the debt secured by the property.
NerdWallet recognized Wells Fargo in its 2026 cash-out refinancing category. <Cite refs={["turn368999search1","turn705376view0"]}/>
Potential advantages
Access to mortgage refinancing services.
Ability to compare a new mortgage structure with an existing loan.
Potential access to home equity, subject to eligibility and underwriting.
What to consider
Cash-out refinancing can increase the loan balance and total interest paid over time. It may also replace a favorable existing rate with a higher rate.
Compare the new APR, closing costs, loan term, and total repayment amount with alternatives such as a home equity loan or home equity line of credit.
Best for: Homeowners exploring cash-out refinancing who meet the lender's requirements.
Official website: Wells Fargo Home Mortgage
4. loanDepot: Best for FHA Mortgage Options
<Entity category="company" value="loanDepot" disambig="US mortgage lending company"/> offers residential mortgage products, including loans backed by the Federal Housing Administration (FHA).
FHA loans are designed to make home financing accessible to eligible borrowers who may not qualify for some conventional mortgage products. They are issued by approved lenders and insured by the federal government.
NerdWallet selected loanDepot as its best FHA mortgage lender for 2026. <Cite refs={["turn368999search1","turn705376view0"]}/>
Why consider loanDepot?
Offers FHA mortgage options.
May be worth comparing for borrowers exploring government-backed financing.
Provides access to mortgage application and lending support.
What to consider
FHA mortgages have program rules and typically involve mortgage insurance costs. A lower down payment does not necessarily mean a lower total borrowing cost.
Compare FHA offers with eligible conventional loans and review the full monthly payment, including insurance and property-related expenses.
Best for: Borrowers exploring FHA financing.
Official website: loanDepot
5. Navy Federal Credit Union: Best for Eligible Military Borrowers
<Entity category="organization" value="Navy Federal Credit Union" disambig="US credit union serving military members and families"/> provides financial services to eligible members of the military community and their families.
The institution offers VA-backed mortgage options for eligible borrowers. VA loans can offer significant benefits, including the possibility of purchasing a home without a required down payment, subject to eligibility and lender approval.
NerdWallet recognized Navy Federal as its best VA mortgage lender for 2026. <Cite refs={["turn368999search1","turn705376view0"]}/>
Potential benefits
Mortgage products designed for eligible military borrowers.
Experience with VA loan requirements.
Options for home purchases and refinancing.
What to consider
Membership eligibility applies, and VA loan eligibility is separate from credit union membership. Some borrowers may also need to pay a VA funding fee unless exempt.
Compare the lender's rate, fees, funding fee, and closing timeline with other VA-approved lenders.
Best for: Eligible service members, veterans, and other qualifying applicants.
Official website: Navy Federal Credit Union
6. Bank of America: Best for Jumbo Mortgages
<Entity category="company" value="Bank of America" disambig="US bank and mortgage lender"/> offers mortgage financing for a range of home purchases, including eligible jumbo mortgages.
A jumbo mortgage exceeds the applicable conforming loan limit for the property's location and year. These loans can be useful when financing a higher-priced property that requires a larger loan than standard conforming limits allow.
NerdWallet selected Bank of America as its best jumbo mortgage lender for 2026. <Cite refs={["turn368999search1","turn705376view0"]}/>
Why consider Bank of America?
Offers jumbo mortgage options.
Provides mortgage services through an established national bank.
May offer banking relationship benefits to qualifying customers.
What to consider
Jumbo loan requirements can be stricter than those for some standard mortgages. Lenders may evaluate credit history, income, assets, down payment, and cash reserves closely.
Review any relationship discounts carefully. A discounted rate is valuable only if the total loan costs and required banking arrangements make financial sense.
Best for: Buyers seeking jumbo mortgage financing for higher-priced properties.
Official website: Bank of America Home Loans
7. Better Mortgage: Worth Comparing for Home Equity Loans
<Entity category="company" value="Better Mortgage" disambig="US digital mortgage and home financing company"/> provides digital home financing services and is worth researching for homeowners who want to compare equity-based borrowing options.
A home equity loan allows eligible homeowners to borrow against the equity they have accumulated in their property. Unlike a home equity line of credit, a traditional home equity loan commonly provides a lump sum with a defined repayment schedule.
NerdWallet selected Better as its best home equity loan lender for 2026. <Cite refs={["turn368999search1","turn705376view0"]}/>
Potential advantages
Digital application tools.
Home equity borrowing options for eligible homeowners.
A separate loan that may preserve the rate on an existing first mortgage.
What to consider
A home equity loan uses your home as collateral. Failure to repay can put the property at risk.
Compare the APR, origination charges, repayment term, and total cost with cash-out refinancing and other financing options.
Best for: Eligible homeowners who want to compare a separate home equity loan.
Official website: Better Mortgage
8. U.S. Bank: Best to Compare for Manufactured Home Financing
<Entity category="company" value="U.S. Bank" disambig="US banking and mortgage lender"/> offers home financing products and may be worth considering for borrowers purchasing certain manufactured homes.
Manufactured home financing can involve different requirements depending on whether the property is permanently attached to land, how it is titled, and whether the transaction qualifies for a particular mortgage program.
NerdWallet selected U.S. Bank as its best manufactured home mortgage lender for 2026. <Cite refs={["turn368999search1","turn705376view0"]}/>
What to review
Whether the property qualifies for the intended mortgage.
Land ownership and foundation requirements.
Down payment and credit requirements.
Interest rate, fees, and property appraisal conditions.
Best for: Buyers who need financing for an eligible manufactured home.
Official website: U.S. Bank
How to Choose the Best Mortgage Lender
A lender's reputation is useful, but the most important question is whether its actual offer suits your circumstances.
1. Compare Interest Rates and APR
The interest rate measures the rate charged on the outstanding principal. The APR is designed to reflect the interest rate plus certain additional loan costs.
Compare written estimates for the same loan amount, term, down payment, and rate structure. A lower advertised interest rate may come with higher fees or discount points.
2. Review Closing Costs
Mortgage costs can include origination charges, appraisal fees, title services, recording charges, prepaid taxes, insurance, and other expenses.
Ask each lender for a Loan Estimate and review the costs line by line. Consider both the cash needed at closing and the total cost over the period you expect to keep the loan.
3. Check Loan Eligibility
Different loan programs have different requirements.
Conventional mortgages: May suit borrowers who meet the lender's credit and financial criteria.
FHA loans: May offer more flexible qualification rules for eligible borrowers.
VA loans: Designed for eligible military borrowers.
USDA loans: Available for qualifying borrowers and properties under program rules.
Jumbo mortgages: Used for loans exceeding applicable conforming limits.
Do not assume a lender's advertised minimum credit score guarantees approval. Income, debts, property details, and other requirements also matter.
4. Consider Customer Service and Closing Times
A mortgage involves document verification, appraisal, underwriting, and legal or title processes. Clear communication can help you respond quickly when the lender requests information.
Ask how you will contact the loan team, how application updates are delivered, and what may delay closing.
5. Get Multiple Offers
Request quotes from at least three lenders when practical. Consider banks, credit unions, online mortgage lenders, and mortgage brokers.
Freddie Mac and other housing experts encourage borrowers to shop around because comparing mortgage offers may produce meaningful savings. <Cite refs={["turn368999search11","turn368999search17"]}/>
When comparing offers, focus on the same loan type and terms so you can make a fair assessment.
What Credit Score Do You Need for a Mortgage?
There is no universal credit score that guarantees mortgage approval. Requirements depend on the lender, mortgage program, down payment, and overall financial profile.
Some programs may permit lower credit scores than others, but applicants with stronger credit may qualify for more favorable pricing. Borrowers should review their credit reports, correct errors, and avoid unnecessary new debt before applying.
A mortgage lender may also assess income stability, debt-to-income ratio, available savings, and the property's value.
Fixed-Rate vs. Adjustable-Rate Mortgages
Choosing between a fixed-rate and adjustable-rate mortgage can affect long-term affordability.
A fixed-rate mortgage keeps the interest rate unchanged throughout its agreed term. This can make principal-and-interest payments more predictable.
An adjustable-rate mortgage may begin with a lower rate but can change after an initial period. If the rate rises, the monthly payment may increase.
Before selecting an adjustable-rate mortgage, understand the first adjustment date, adjustment frequency, rate caps, and highest possible payment. Compare the potential cost under different rate scenarios rather than relying only on the initial rate.
How to Get Mortgage Preapproval
Mortgage preapproval can help you estimate the amount a lender may be willing to finance and demonstrate to sellers that you have started the financing process.
The process commonly involves these steps:
Review your credit reports and financial situation.
Gather income records, bank statements, and information about existing debts.
Compare lenders and submit preapproval applications.
Review the estimated loan amount, rate assumptions, fees, and conditions.
Obtain a property-specific Loan Estimate after proceeding with a particular home and mortgage application.
Preapproval is not a final guarantee of financing. The lender must still verify the application, assess the property, and complete underwriting.
Common Mortgage Mistakes to Avoid
Choosing a Lender Based Only on Advertising
Promotional rates may depend on credit score, loan type, discount points, or other conditions. Compare offers based on your actual circumstances.
Borrowing the Maximum Amount Offered
A lender's approval amount does not necessarily represent a comfortable household budget. Account for property taxes, insurance, maintenance, utilities, and emergency savings.
Ignoring Mortgage Insurance
Some mortgages require mortgage insurance or program-specific fees. Include these costs when comparing monthly payments and long-term affordability.
Skipping the Fine Print
Review rate-lock terms, prepayment rules, closing costs, and conditions that could affect your payment or loan approval.
Failing to Shop Around
Even when several lenders offer the same loan type, their rates, fees, and service may differ. Comparing multiple written estimates can help you make a better-informed decision.
Frequently Asked Questions
Who is the best mortgage lender in 2026?
NerdWallet named Truist its overall best mortgage lender for 2026 and Rocket Mortgage its best lender for first-time homebuyers. However, the right lender depends on your location, credit profile, loan type, fees, and financial goals. <Cite refs={["turn368999search1","turn705376view0"]}/>
Which mortgage lender is best for first-time buyers?
Rocket Mortgage is one option to compare because NerdWallet selected it for first-time homebuyers in 2026. Buyers should also compare local lenders and banks, including any eligible down payment assistance programs.
Can I get a mortgage with a low credit score?
Possibly. Some mortgage programs and lenders consider applicants with lower credit scores, but approval and pricing depend on several factors. Review the full cost and eligibility rules before applying.
Should I choose a bank or an online mortgage lender?
Banks may offer in-person service and relationship benefits, while online lenders may provide convenient digital applications. Neither is automatically cheaper. Compare APR, fees, service, and loan terms.
Is refinancing a mortgage worth it?
Refinancing may be worthwhile if the new terms reduce costs or better fit your financial goals. Consider closing costs, the new rate, the remaining term, and how long you expect to keep the mortgage.
How many mortgage lenders should I compare?
Comparing at least three lenders is a practical starting point. Request comparable written estimates and evaluate both the immediate closing costs and longer-term borrowing expenses.
Final Thoughts
The best mortgage lenders in 2026 offer different benefits for different borrowers. Truist may be a strong starting point for broad mortgage needs, Rocket Mortgage is worth comparing for first-time buyers, and specialized lenders may be more appropriate for FHA, VA, jumbo, refinancing, or home equity financing.
Before making a decision, compare written offers, examine APR and fees, verify eligibility, and choose a payment that fits your budget. A little research before signing can help you avoid unnecessary costs over the life of your mortgage.
Disclaimer: This article is for educational purposes only and is not individualized financial advice. Lender rankings, interest rates, fees, and eligibility requirements can change. Confirm current terms directly with lenders and consult a qualified financial professional when appropriate.


