Finding the best credit card can be difficult because there is no single card that is perfect for everyone. The right credit card depends on your spending habits, financial goals, income, credit history, preferred rewards, fees, and how you plan to use the card.
Some credit cards are designed for cashback, while others focus on travel rewards, shopping benefits, low fees, business expenses, or building credit. A card that works well for a frequent traveler may not be the right choice for someone who mainly uses a card for groceries and everyday purchases.
When comparing the best credit cards, it is important to look beyond attractive advertisements and introductory offers. Interest rates, annual fees, foreign transaction charges, reward limits, eligibility requirements, and repayment terms can have a significant impact on the overall value of a card.
This guide explains what to look for when comparing credit cards and how to choose an option that matches your financial needs.
What Are the Best Credit Cards?
The term best credit cards generally refers to credit cards that offer useful features, competitive costs, rewards, benefits, or flexible payment options for a particular type of customer.
However, "best" is highly dependent on individual circumstances.
For example, one person may prioritize:
Cashback on everyday purchases
Travel rewards
Airline miles
Low annual fees
Business expenses
Online shopping benefits
Building a credit history
Introductory offers
Another person may care more about a low interest rate or avoiding unnecessary fees.
Therefore, comparing cards based on your own financial priorities is usually more useful than choosing a card simply because it is advertised as one of the best.
Types of Credit Cards to Consider
Different credit cards are designed for different purposes. Understanding the major categories can make comparison easier.
1. Cashback Credit Cards
Cashback credit cards provide rewards based on eligible purchases. The cashback rate may differ depending on the spending category.
Some cards may provide higher rewards for groceries, fuel, dining, online shopping, or other categories.
Cashback cards can be attractive to people who prefer simple rewards instead of travel points or airline miles.
When comparing cashback cards, check:
Cashback percentage
Eligible purchases
Monthly or annual limits
Redemption requirements
Expiration rules
Annual fees
A card with a high advertised cashback rate may not necessarily provide the greatest overall value if it has significant fees or restrictive conditions.
2. Travel Credit Cards
Travel credit cards are designed for people who frequently travel.
Depending on the card, benefits may include:
Travel points
Airline miles
Hotel rewards
Airport lounge access
Travel insurance
Foreign transaction benefits
Travel-related discounts
Frequent travelers should pay particular attention to foreign transaction fees, reward redemption options, travel restrictions, and annual fees.
The best travel card for one traveler may not be suitable for another because airline preferences, destinations, spending patterns, and travel frequency vary.
3. Low-Fee Credit Cards
Some consumers prioritize minimizing fees rather than earning rewards.
Low-fee cards may be useful for people who want a straightforward credit card without paying a high annual fee.
When evaluating these cards, look beyond the annual fee. Check for:
Late payment fees
Cash advance fees
Foreign transaction fees
Balance transfer fees
Replacement card charges
Other account fees
A card advertised as low-cost may still have other charges that should be considered.
4. Rewards Credit Cards
Rewards credit cards allow customers to earn points or other benefits from eligible spending.
Points may potentially be redeemed for:
Travel
Merchandise
Gift cards
Statement credits
Discounts
Other rewards
The value of points depends on the issuer's redemption system. Consumers should review how many points are required for different rewards before assuming that a high rewards rate represents high value.
5. Secured Credit Cards
Secured credit cards generally require a refundable security deposit.
They may be available to consumers who are establishing or rebuilding their credit history, depending on the issuer and local eligibility requirements.
When considering a secured card, check whether the issuer reports account activity to relevant credit bureaus and understand the deposit, fees, interest rate, and upgrade policies.
6. Business Credit Cards
Business credit cards are designed for business-related spending.
They may provide features such as:
Expense tracking
Employee cards
Business rewards
Spending controls
Accounting integrations
Purchase management
Business owners should carefully review the terms to understand personal liability, employee spending responsibilities, fees, and how the account is reported.
7. Student Credit Cards
Student credit cards are designed for eligible students who are beginning to develop credit.
They may have simpler rewards structures or eligibility requirements tailored toward students.
Students should focus on manageable credit limits, reasonable fees, responsible repayment, and understanding how the account affects their credit history.
How to Compare the Best Credit Cards
Choosing a credit card requires more than comparing rewards. Several important factors should be evaluated.
Interest Rate
The interest rate can be one of the most important costs associated with a credit card.
If you regularly carry a balance, a card's interest rate can have a significant impact on the total amount you repay.
Always review the applicable APR and understand how interest is calculated.
Annual Fee
Some credit cards charge an annual fee while others do not.
A card with an annual fee may still be worthwhile for some users if the benefits exceed the cost. However, consumers should calculate the actual value they expect to receive rather than assuming that more benefits automatically mean better value.
Rewards Rate
Compare how many points, miles, or cashback rewards you receive for different types of spending.
For example, one card might offer higher rewards for travel while another may provide more rewards for groceries or online shopping.
Choose a rewards structure that matches your actual spending habits.
Foreign Transaction Fees
People who travel internationally or purchase products from foreign merchants should check whether the card charges foreign transaction fees.
These fees can add to the cost of international purchases.
Introductory Offers
Credit cards may offer introductory rewards, promotional interest rates, or other incentives.
Before applying, read the conditions carefully.
Some promotional offers require a minimum amount of spending within a specified period. If meeting that requirement would encourage you to spend beyond your normal budget, the offer may not provide meaningful value.
Credit Limit
A credit card issuer determines a credit limit based on its eligibility and underwriting criteria.
A larger credit limit does not mean you should spend more.
The important consideration is whether your spending remains within your ability to repay.
Acceptance
A credit card is only useful where it is accepted.
If you frequently travel internationally, check whether the card network is widely accepted in your destinations.
Best Credit Cards for Everyday Spending
For everyday spending, look for a card with rewards that match your regular purchases.
Potential spending categories include:
Groceries
Fuel
Dining
Online shopping
Utility payments
Transportation
Household expenses
A simple cashback card can be convenient for someone who does not want to track multiple reward categories.
Another option may be a rewards card that offers higher points for specific categories.
The key is to compare actual rewards earned against fees and other costs.
Best Credit Cards for Travel
Travelers may prioritize cards offering travel-related benefits.
When comparing travel cards, consider:
Airline Benefits
If you frequently fly with a particular airline or airline network, check whether the card's rewards are useful for those flights.
Hotel Benefits
Some cards provide hotel points, discounts, or other accommodation-related benefits.
Airport Benefits
Certain premium cards may offer airport lounge access or other travel services.
Foreign Transaction Costs
Frequent international travelers should carefully review foreign transaction fees and currency conversion terms.
Travel Insurance
Some cards may provide travel-related insurance or protections, subject to specific conditions.
Always read the benefit terms before relying on insurance coverage.
Best Credit Cards for Cashback
Cashback cards can be useful for consumers who want straightforward rewards.
When comparing cashback cards, look at the actual percentage returned on your most common purchases.
For example, a card offering a higher cashback rate on groceries may be more useful to a household that spends heavily on groceries than a card offering higher rewards on travel.
Also check whether cashback is:
Unlimited
Capped
Category-specific
Automatically credited
Redeemable only after reaching a minimum amount
These details can significantly affect the practical value of the rewards.
Best Credit Cards for Building Credit
Consumers who are new to credit or rebuilding their credit may have different priorities.
Instead of focusing primarily on rewards, consider:
Eligibility requirements
Credit reporting
Fees
Interest rate
Deposit requirements
Credit limit
Payment flexibility
Responsible use is generally more important than having a large number of rewards.
Making payments on time and keeping spending manageable can help establish good financial habits.
Best Credit Cards for Businesses
Businesses often have different credit card requirements from individual consumers.
A business card can make it easier to separate business and personal expenses.
When comparing business credit cards, consider:
Employee card controls
Expense reporting
Business rewards
Annual fees
Spending limits
Accounting integrations
Purchase protections
Business owners should also review whether the card requires a personal guarantee or creates personal liability.
Credit Card Rewards: What to Watch For
Rewards can make a credit card more attractive, but they should not be the only factor in a decision.
Some rewards programs have conditions such as:
Spending thresholds
Category restrictions
Redemption minimums
Expiration dates
Reward caps
Blackout dates
Limited redemption options
Read the rewards terms carefully.
A reward is only valuable if you can realistically use it.
Understanding Credit Card Fees
Credit card fees can significantly affect the overall cost of a card.
Common fees include:
Annual Fee
A recurring fee charged for maintaining the card.
Late Payment Fee
A charge that may apply when the required payment is not made by the due date.
Cash Advance Fee
A fee that may apply when obtaining cash through a credit card.
Foreign Transaction Fee
A fee that may apply to transactions processed outside the card's home country or in foreign currency.
Balance Transfer Fee
A fee that may apply when transferring a balance from one credit card to another.
Always review the card's fee schedule before applying.
How to Use a Credit Card Responsibly
Even the most attractive credit card can become expensive if used irresponsibly.
Pay on Time
Make at least the required payment by the due date.
Pay the Full Statement Balance When Possible
Paying the full statement balance can help avoid interest on eligible purchases under many card agreements.
Track Spending
Review transactions regularly and compare them with your monthly budget.
Avoid Unnecessary Debt
Do not use a credit card to finance purchases that you cannot reasonably repay.
Monitor Your Account
Check statements and transaction alerts for unauthorized activity.
Understand Your Benefits
Know exactly what your rewards and protections include instead of assuming that every advertised benefit applies automatically.
Common Mistakes When Choosing a Credit Card
One common mistake is choosing a card based only on a large introductory bonus.
Another is ignoring annual fees because the rewards appear attractive.
Consumers may also overlook foreign transaction fees, spending limits, interest rates, or redemption restrictions.
Other mistakes include:
Applying for too many cards at once
Spending more to earn rewards
Carrying expensive balances
Ignoring account statements
Making only minimum payments
Using cash advances without understanding the cost
Taking time to compare the complete terms can help avoid these problems.
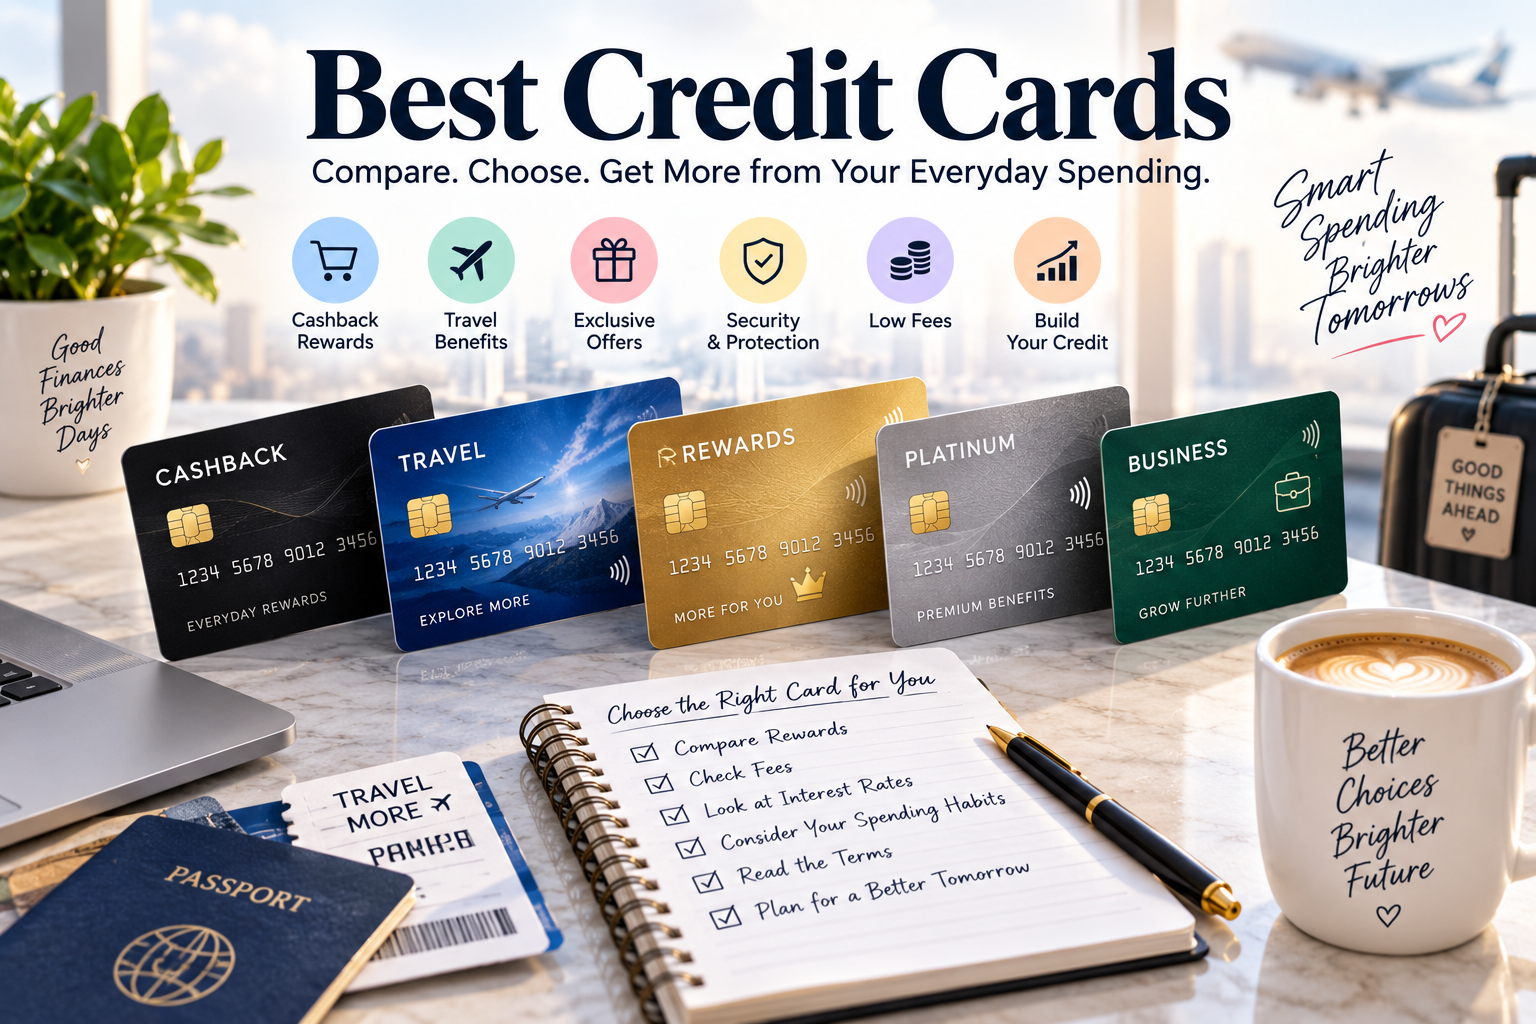
A Simple Credit Card Comparison Checklist
Before applying for a card, ask:
What is the annual fee?
What is the interest rate?
How do the rewards work?
What purchases qualify for rewards?
Are rewards capped?
What are the foreign transaction fees?
What are the late payment charges?
What is the credit limit?
What are the eligibility requirements?
Are there introductory offers?
What are the conditions for receiving those offers?
Can the rewards be easily redeemed?
Does the card offer useful protections?
Can I comfortably repay what I spend?
Answering these questions can make comparing different cards much easier.
Are the Best Credit Cards Always Premium Cards?
Not necessarily.
Premium credit cards may offer extensive rewards and additional benefits, but they can also have higher annual fees and more complicated terms.
A basic credit card with low fees may be more appropriate for someone who wants simple payment functionality.
The right card depends on how the card will actually be used.
Final Thoughts
The best credit cards are not necessarily the cards with the biggest rewards or the most impressive advertising. The right choice depends on your spending habits, financial circumstances, repayment ability, and personal priorities.
When comparing credit cards, consider the complete package: interest rates, annual fees, rewards, foreign transaction charges, credit limits, introductory offers, eligibility requirements, and additional benefits.
For everyday shoppers, cashback may be useful. Frequent travelers may prefer travel rewards. Someone building credit may prioritize affordability and responsible credit reporting. Business owners may look for expense-management tools and employee controls.
Most importantly, a credit card should be used within your ability to repay. Rewards and benefits should complement responsible financial management rather than encourage unnecessary spending.
By carefully comparing card terms and understanding how each feature works, consumers can make a more informed decision about which credit card fits their individual needs.
Frequently Asked Questions About the Best Credit Cards
What is the best credit card?
There is no single credit card that is best for everyone. The appropriate card depends on factors such as spending habits, fees, rewards, credit history, travel needs, and repayment ability.
Which credit card is best for everyday spending?
A cashback or rewards card may suit everyday spending, particularly if its rewards categories match your regular purchases. Compare the rewards with annual fees and other costs.
What is the best credit card for travel?
Travel cards may be suitable for frequent travelers because they can offer points, miles, hotel benefits, lounge access, or travel protections. Compare the benefits, fees, redemption rules, and foreign transaction costs.
What is the best credit card for cashback?
The appropriate cashback card depends on where you spend money most frequently. Compare cashback rates, category restrictions, spending caps, redemption rules, and annual fees.
Are credit cards with annual fees worth it?
An annual-fee card may be worthwhile if the benefits and rewards you actually use exceed the cost. Calculate the expected value before applying.
What should I look for in a credit card?
Consider the interest rate, annual fee, rewards, foreign transaction fees, credit limit, eligibility requirements, introductory offers, and additional benefits.
Can a credit card help build credit?
In countries with credit reporting systems, responsible credit card use and timely payments may contribute to a positive credit history. Reporting practices vary by country and issuer.
Is a rewards credit card always better?
Not necessarily. A rewards card may have higher fees or interest costs. Rewards are useful only when the benefits fit your spending habits and you can manage the account responsibly.
Should I choose a card with a large sign-up bonus?
A sign-up bonus can be valuable, but check the eligibility requirements and spending threshold. Avoid spending more than you can comfortably repay simply to qualify for a bonus.
Are no-annual-fee credit cards better?
A no-annual-fee card can reduce ongoing costs, but other features such as rewards, interest rates, and transaction fees should also be considered.
What is the best credit card for students?
Eligible students may consider cards designed for people beginning to establish credit. Fees, credit limits, reporting practices, and repayment terms should be reviewed carefully.
What is a secured credit card?
A secured credit card generally requires a refundable deposit and may be designed for people establishing or rebuilding credit, depending on the issuer's requirements.
Can I have multiple credit cards?
Yes, some people have multiple cards. However, each additional account creates another payment obligation to manage. Consider your budget, fees, debt levels, and ability to make payments before opening another account.
How can I avoid credit card debt?
Spend within your budget, monitor your balance, make payments on time, and avoid carrying balances that you cannot comfortably repay. Paying the full statement balance when possible can help reduce interest costs on eligible purchases.
Should I choose a credit card based only on rewards?
No. Rewards are only one factor. Interest rates, fees, credit limits, eligibility requirements, and repayment terms are also important.
How often should I compare credit cards?
It can be useful to review your credit card periodically, particularly if your spending habits, income, travel patterns, or financial goals change. Always check current terms directly with the issuer before making a decision.