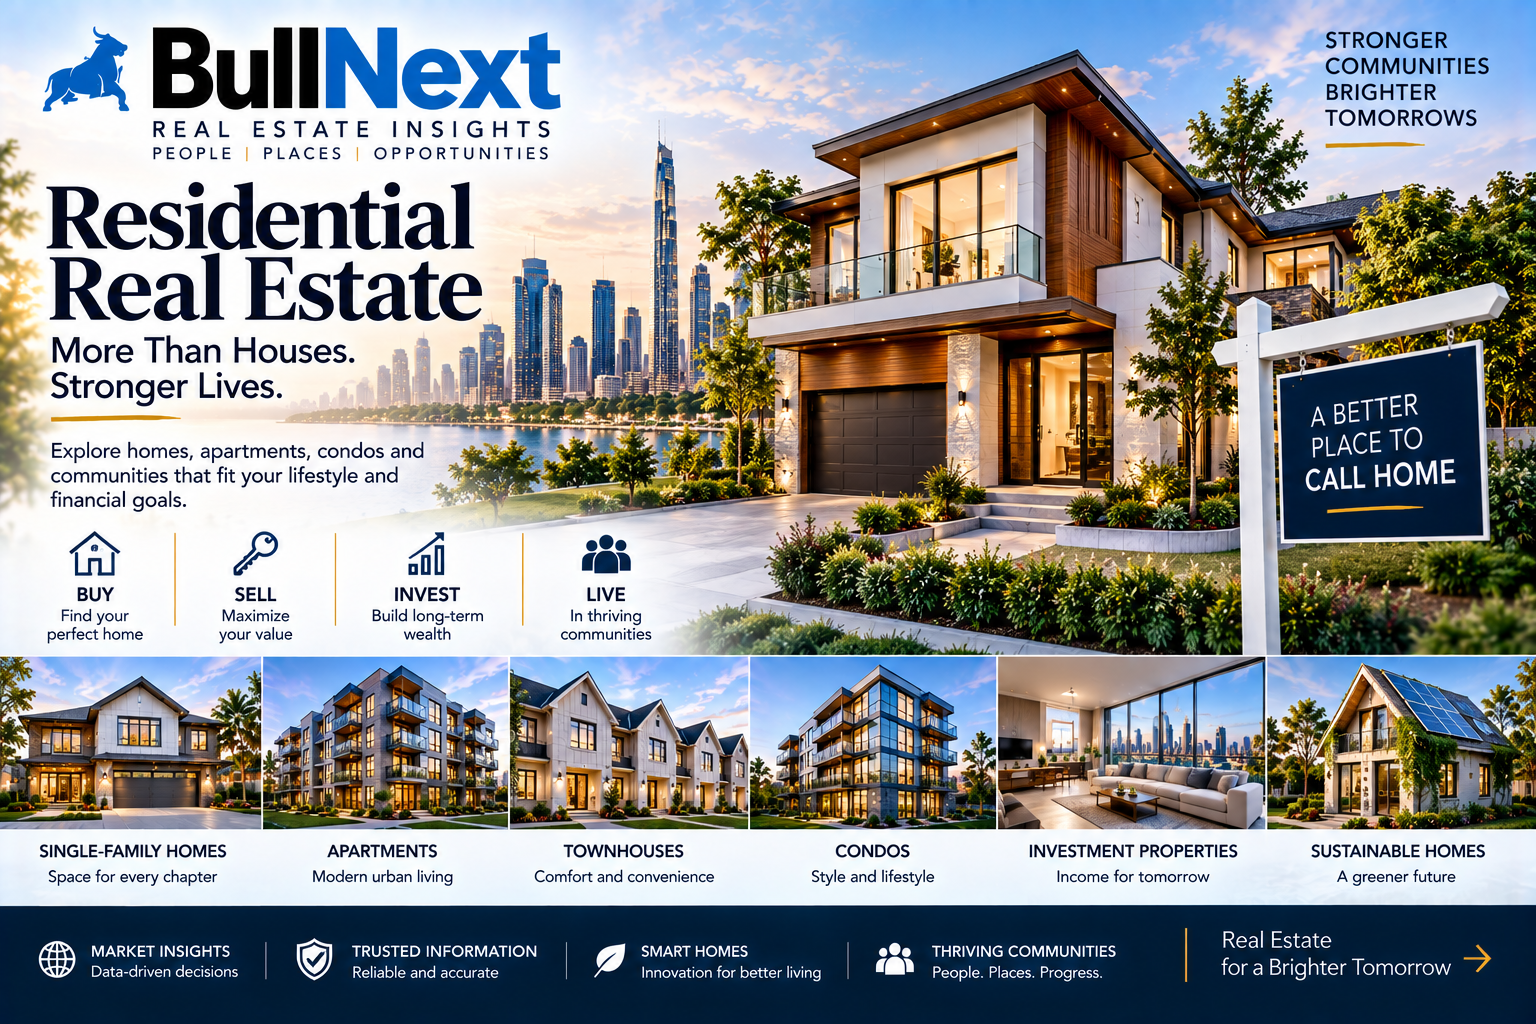
Residential real estate is one of the most visible and important segments of the global property industry. It covers the places where people live, from detached houses and apartments to condominiums, townhouses, and multifamily communities.
For individuals and families, residential property can represent a home, a long-term financial commitment, and an important part of personal wealth. For investors, residential real estate can provide rental income and potential appreciation. For developers, it represents an opportunity to create housing communities that respond to changing population and lifestyle needs.
However, residential real estate is not simply about buying a house. Successful property decisions require an understanding of location, affordability, financing, property condition, market supply, neighborhood development, taxes, insurance, maintenance, and future demand.
What Is Residential Real Estate?
Residential real estate consists of land and buildings primarily intended for people to live in.
Major categories include:
Single-family houses
Condominiums
Apartments
Townhouses
Duplexes
Multifamily buildings
Manufactured homes
Vacation homes
Second homes
Residential properties can serve different purposes. A buyer may purchase a home for personal use, while another person may purchase a property to rent to tenants. Developers may construct entire residential communities, while investors may build portfolios containing multiple rental properties.
The residential sector therefore includes homeowners, buyers, sellers, landlords, tenants, developers, lenders, agents, property managers, inspectors, appraisers, and other professionals.
Why Residential Real Estate Is Important
Housing plays a central role in communities and economies.
Demand for homes is influenced by population growth, household formation, employment, income, migration, financing conditions, construction activity, and local infrastructure.
Residential property can also represent a major financial asset. Homeowners who have mortgages may build equity as loan principal is repaid. Property values can also change over time based on local and broader market conditions.
However, property ownership comes with responsibilities. Mortgage payments are only one part of the cost of owning a home. Taxes, insurance, maintenance, utilities, repairs, and association fees can also affect affordability.
Different Types of Residential Property
Single-Family Homes
Single-family homes are generally designed for one household. They may provide private yards, garages, outdoor areas, and greater control over the property.
These homes are common in suburban, urban, and rural communities.
Apartments
Apartments contain multiple residential units within a building or development. Residents generally rent their units rather than owning the individual apartment.
Apartment markets can be influenced by employment, population growth, rental affordability, and the supply of available units.
Condominiums
Condominiums combine individual ownership of a unit with shared ownership or responsibility for common areas.
Common facilities may include:
Parking
Elevators
Gyms
Swimming pools
Lobbies
Landscaping
Security systems
Condo owners commonly pay association fees for the maintenance of shared areas.
Townhouses
Townhouses typically share walls with neighboring properties but may offer multiple floors and private entrances.
They can appeal to households looking for more space than a typical apartment while preferring a community-style environment.
Multifamily Properties
Multifamily properties contain multiple residential units.
They can range from small two-unit buildings to large apartment complexes. Multifamily housing is particularly important in areas where population growth and housing demand create pressure for additional residential supply.
Location Remains a Major Consideration
A property's location can influence its convenience, desirability, rental demand, and potential resale appeal.
When researching a residential property, buyers should examine more than the immediate street.
Important factors can include:
Employment opportunities
Transportation
Schools
Healthcare
Shopping
Restaurants
Parks
Public services
Infrastructure
Neighborhood development
Future construction
Two homes with similar sizes and features can have very different market characteristics because they are located in different neighborhoods.
This is why residential property research should include both the building and its surrounding community.
Housing Affordability
Affordability is one of the biggest considerations for residential buyers.
A realistic housing budget should account for the total cost of ownership rather than simply the purchase price.
Potential expenses include:
Down payment
Mortgage principal and interest
Property taxes
Homeowners insurance
Mortgage insurance
Utilities
Maintenance
Repairs
Homeowners association fees
Closing expenses
Mortgage rates can have a significant impact on purchasing power. Freddie Mac's survey showed the average U.S. 30-year fixed mortgage rate at 6.95% on September 17, 2026, while the 15-year fixed rate averaged 6.26%.
Mortgage rates can change over time, so buyers should evaluate financing using current offers rather than relying on historical rates.
Mortgage Financing for Residential Property
Most buyers who finance a home use a mortgage.
The mortgage amount, interest rate, term, down payment, fees, and borrower qualifications can all influence the overall cost.
Common mortgage structures include:
Fixed-rate mortgages
Adjustable-rate mortgages
Government-backed mortgage programs
Conventional mortgages
Specialized financing programs
When comparing mortgages, buyers should look beyond the headline interest rate.
The annual percentage rate, loan fees, closing costs, monthly payment, and total borrowing costs can provide additional information for comparison.
Getting Ready to Buy a Home
Preparation can make the home-buying process more manageable.
Potential buyers can begin by reviewing:
Income
Monthly expenses
Existing debt
Credit history
Available savings
Down payment
Emergency funds
Expected closing costs
Mortgage preapproval can also provide an indication of how much financing a lender may be willing to provide.
However, a lender's maximum loan amount does not necessarily represent a comfortable personal budget. Buyers should consider their broader financial obligations and future expenses.
How to Research a Residential Property
Before making an offer, buyers should conduct detailed research.
Examine Comparable Properties
Look at similar homes that have recently sold or are currently listed in the same area.
Study the Neighborhood
Research transportation, amenities, schools, employment centers, development projects, and local services.
Review Property History
Where available, examine previous sales, renovations, permits, property taxes, and other relevant records.
Consider Future Needs
A property should work not only for today's lifestyle but also for foreseeable changes such as family growth, remote work, aging, or changing transportation needs.
Why Home Inspections Matter
A property can look excellent during a viewing while still having hidden problems.
A professional home inspection can examine areas such as:
Roof
Foundation
Plumbing
Electrical systems
Heating and cooling
Windows
Floors
Attic
Basement
Appliances
Visible structural components
The Consumer Financial Protection Bureau recommends arranging an independent inspection as early as possible after choosing a home so buyers have time to understand and address potential problems.
An inspection is different from an appraisal. An inspection focuses primarily on physical condition, while an appraisal provides an opinion of property value.
Understanding Property Appraisals
An appraisal helps estimate the market value of a property.
For financed purchases, lenders may use an appraisal to evaluate whether the property provides sufficient collateral for the loan.
If an appraisal is lower than the purchase price, the transaction may require additional negotiation or financing adjustments depending on the contract and loan structure.
Buyers should therefore understand the difference between what a seller is asking, what a buyer is willing to pay, and what available valuation evidence indicates.
The Role of Closing Costs
Residential property transactions involve costs beyond the property's sale price.
Depending on the transaction and jurisdiction, these can include:
Loan-related fees
Appraisal fees
Title services
Recording fees
Taxes
Insurance
Prepaid expenses
Escrow-related costs
In U.S. mortgage transactions, the Loan Estimate provides information about expected loan terms and costs, while the Closing Disclosure provides the final loan terms and closing costs before completion.
Understanding these documents can help buyers identify unexpected changes before closing.
Selling Residential Real Estate
Selling a residential property involves several stages.
The seller typically needs to:
Research the local market
Establish an asking price
Prepare the property
Photograph and market the home
Manage showings
Review offers
Negotiate terms
Complete inspections and other requirements
Prepare for closing
Pricing is particularly important.
An asking price that is significantly above comparable market evidence may reduce buyer interest, while an unnecessarily low price may affect potential proceeds.
Local market conditions should therefore be considered when determining a listing strategy.
Preparing a Property for Sale
Sellers do not necessarily need to undertake major renovations before listing.
Simple improvements can sometimes improve presentation, including:
Decluttering
Deep cleaning
Improving landscaping
Repainting heavily worn areas
Repairing visible damage
Improving lighting
Organizing storage
Updating property photography
The appropriate improvements depend on the property's condition, buyer expectations, budget, and local competition.
Residential Real Estate as an Investment
Residential property is also an important investment category.
An investor may purchase a property with the intention of generating rental income or benefiting from potential long-term appreciation.
Investment analysis should consider both revenue and expenses.
Potential income may come from:
Monthly rent
Parking fees
Storage income
Other permitted property-related income
Expenses may include:
Mortgage payments
Property taxes
Insurance
Maintenance
Repairs
Property management
Utilities
Vacancy
Legal and administrative costs
A property that produces significant rental income can still have weak cash flow if expenses and financing costs are high.
Rental Property Management
Owning a rental property involves more than collecting rent.
Property owners may need to manage:
Tenant applications
Lease agreements
Maintenance
Repairs
Inspections
Rent collection
Legal compliance
Vacancies
Emergency situations
Some investors manage properties themselves, while others hire professional property managers.
The choice can depend on portfolio size, location, time availability, and the complexity of the property.
Technology in Residential Real Estate
Technology is changing nearly every stage of the residential property process.
Buyers can now use digital platforms to:
Search listings
Compare properties
Explore neighborhoods
View virtual tours
Calculate mortgage payments
Contact agents
Submit documents
Property owners can use technology for:
Digital rent collection
Maintenance requests
Smart locks
Security systems
Energy monitoring
Property management
Artificial intelligence and data analytics are also increasingly being used to organize property information and support market research.
Technology can improve efficiency, but important property, legal, and financial information should still be independently verified.
Smart Homes and Modern Living
Smart-home technology is becoming an increasingly visible feature of residential properties.
Examples include:
Smart thermostats
Connected lighting
Smart locks
Security cameras
Video doorbells
Automated appliances
Energy monitoring systems
These technologies can improve convenience and, in some cases, help homeowners monitor energy consumption.
However, buyers should consider the cost, compatibility, privacy, cybersecurity, and maintenance requirements of connected devices.
Sustainability and Residential Property
Energy efficiency is another growing consideration in residential real estate.
Potential features include:
Energy-efficient windows
Better insulation
Efficient heating and cooling
Solar panels
Water-saving fixtures
Efficient appliances
Sustainable building materials
The financial impact of these features depends on local energy prices, climate, installation costs, incentives, and property characteristics.
For some buyers, sustainability can also contribute to long-term lifestyle preferences and property appeal.
Residential Real Estate and Changing Demographics
Housing demand changes as populations and lifestyles evolve.
Different generations may have different preferences regarding:
Home size
Location
Transportation
Outdoor space
Technology
Accessibility
Community amenities
Proximity to employment
Rental versus ownership
Remote and hybrid work have also influenced the way some households think about home offices, commuting distances, and residential space.
Developers and investors therefore need to monitor demographic changes when planning future residential projects.
Infrastructure and Property Markets
Infrastructure can influence residential development.
New roads, public transportation, schools, healthcare facilities, shopping areas, and employment centers can affect the attractiveness of surrounding communities.
However, infrastructure projects can also create temporary disruptions.
Buyers and investors should investigate both existing infrastructure and publicly announced future projects before making major property decisions.
Residential Real Estate Market Conditions in 2026
The U.S. residential market continues to face affordability and financing challenges in 2026.
In September 2026, the average 30-year fixed mortgage rate reached 6.95% according to Freddie Mac.
Recent reporting also showed that U.S. pending home sales increased 0.3% in August but remained 4.7% below the same month a year earlier, illustrating continued softness in transaction activity.
These figures demonstrate why national housing data should be viewed in context. Conditions can vary significantly between cities, states, neighborhoods, and property types.
Buyers should therefore combine national information with local data when evaluating a specific residential market.
Common Residential Real Estate Risks
Residential property can provide valuable opportunities, but it also carries risks.
Market Risk
Property values can decline or remain flat.
Interest Rate Risk
Changing mortgage rates can affect affordability and refinancing costs.
Maintenance Risk
Unexpected repairs can create substantial expenses.
Vacancy Risk
Rental-property owners may experience periods without tenants.
Location Risk
Changes in employment, infrastructure, neighborhood conditions, or local demand can influence property performance.
Liquidity Risk
Selling property can take time and involves transaction costs.
Understanding these risks can help buyers and investors create more realistic financial plans.
A Smart Residential Property Evaluation Framework
A useful way to analyze a property is to examine five areas:
1. Location
Study the neighborhood, transportation, services, employment, and future development.
2. Property
Review condition, size, layout, age, features, and maintenance requirements.
3. Financing
Compare mortgage terms, rates, fees, down payment requirements, and total borrowing costs.
4. Market
Research comparable properties, supply, demand, rental conditions, and recent sales.
5. Future
Consider how the property may fit changing personal needs and market conditions.
This framework can help buyers move beyond emotional impressions and examine the property more systematically.
The Future of Residential Real Estate
The future of residential real estate will likely be influenced by technology, demographics, affordability, construction, infrastructure, and changing consumer preferences.
Smart homes may become more connected. Energy efficiency may become increasingly important. Digital transactions may continue reducing paperwork and improving convenience.
At the same time, traditional fundamentals will remain important.
People will continue to care about location, affordability, property quality, neighborhood services, transportation, and access to employment.
Technology may change how homes are bought and managed, but it does not eliminate the need for careful property research.
Final Thoughts
Residential real estate connects housing, finance, investment, technology, and community development.
Whether someone is buying a first home, selling an existing property, purchasing a rental, or researching a housing market, understanding the fundamentals can make the process more manageable.
A successful residential property decision begins with realistic financial planning and continues with careful research into the property, neighborhood, financing, market conditions, and future needs.
Home inspections, appraisals, financing comparisons, market research, and careful review of transaction documents can all contribute to better-informed decisions.
Ultimately, residential real estate is about more than buildings. It is about the places where people live, build communities, manage finances, and plan for the future.
Frequently Asked Questions
What is residential real estate?
Residential real estate includes properties primarily designed for people to live in, such as houses, apartments, condos, townhouses, and multifamily properties.
What are the main types of residential property?
Major types include single-family homes, apartments, condominiums, townhouses, duplexes, multifamily properties, manufactured homes, and vacation properties.
What should I consider before buying a home?
Consider affordability, financing, location, property condition, taxes, insurance, maintenance, neighborhood characteristics, infrastructure, and future needs.
Why is a home inspection important?
A professional inspection can identify physical problems that may not be obvious during a normal property viewing. The CFPB recommends arranging an independent inspection early enough to address potential issues before closing.
What is the difference between an appraisal and an inspection?
An appraisal provides an opinion of a property's value, while an inspection primarily examines the physical condition of the property.
Can residential real estate generate rental income?
Yes. Owners can rent residential properties to tenants, although rental income needs to be evaluated alongside financing, maintenance, taxes, insurance, vacancies, and management costs.
What affects residential property value?
Location, property condition, size, comparable sales, housing supply, buyer demand, infrastructure, employment, and broader economic conditions can all influence value.
Is residential real estate a guaranteed investment?
No. Property values and rental income can change, and investors can face vacancies, maintenance costs, financing expenses, taxes, and other risks.
How do mortgage rates affect home buying?
Higher mortgage rates generally increase borrowing costs and can reduce the amount of housing a buyer can afford at a given monthly payment. Current rates should be checked when evaluating financing.
What is the future of residential real estate?
Residential real estate is likely to continue evolving through smart-home technology, energy efficiency, digital transactions, demographic changes, new housing development, and changing affordability conditions.