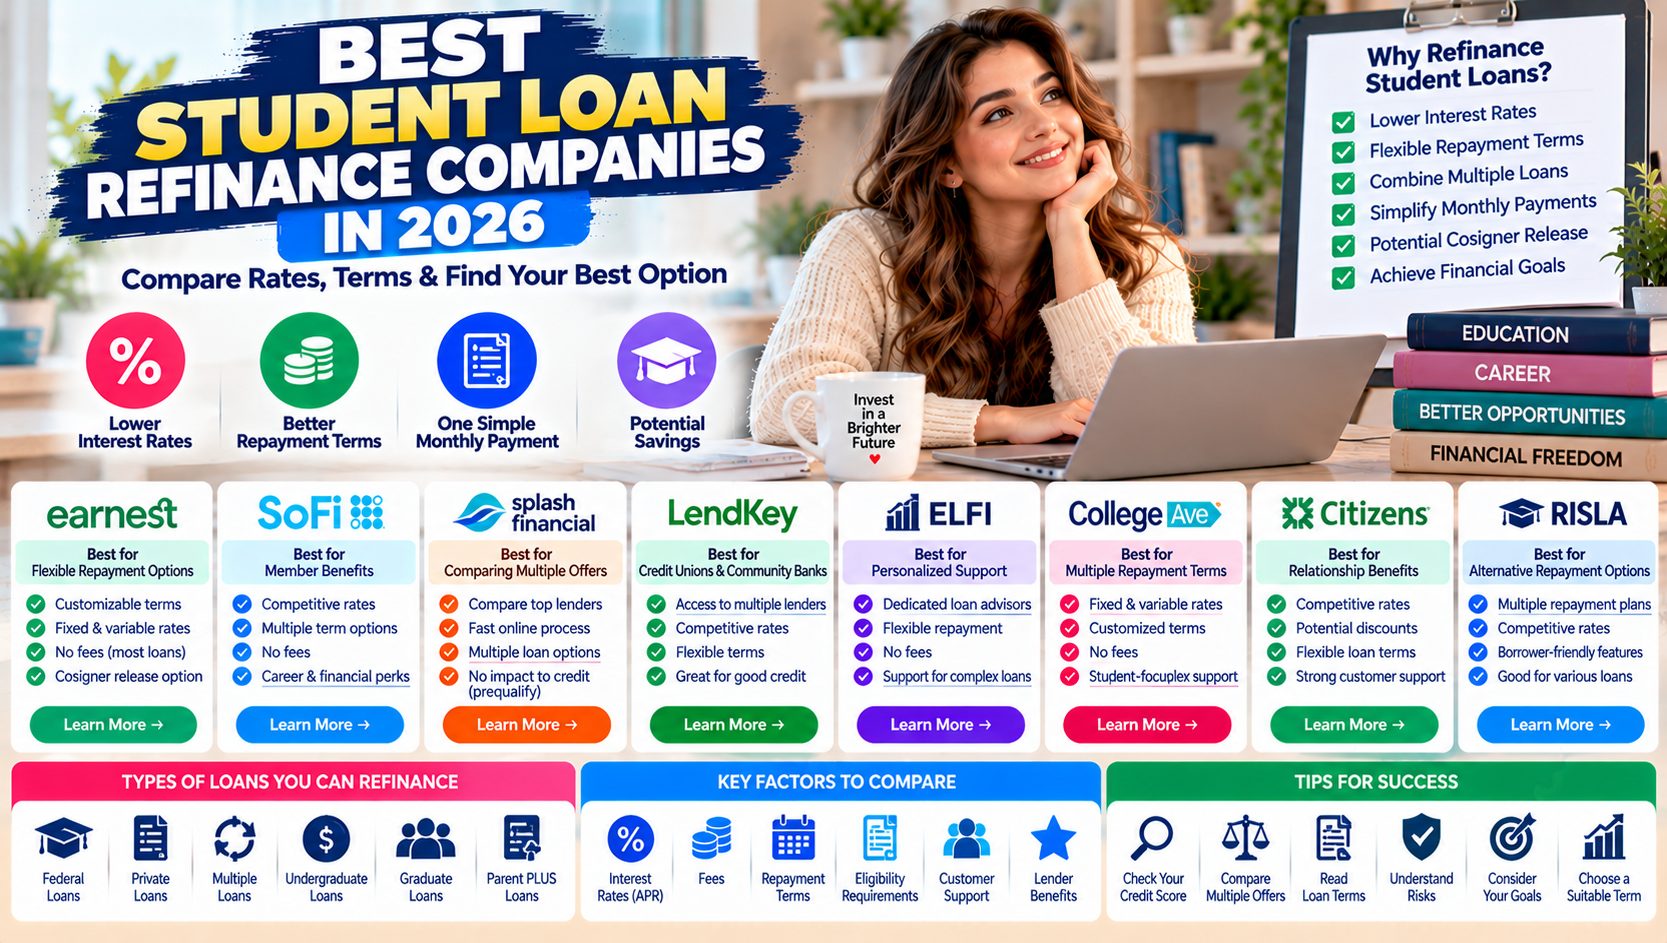
Best Student Loan Refinance Companies in 2026: Compare Rates, Terms, and Benefits
Meta Title: Best Student Loan Refinance Companies in 2026
Meta Description: Compare the best student loan refinance companies in 2026. Explore interest rates, eligibility, repayment terms, benefits, and risks before refinancing.
URL Slug: /best-student-loan-refinance-companies/
Primary Keyword: student loan refinancing
Secondary Keywords: best student loan refinance companies, student loan refinance rates, refinance student loans, private student loan refinancing, student loan repayment options, student loan interest rates
Introduction
Student loans can be a significant financial responsibility for graduates and professionals. High interest rates, multiple monthly payments, and lengthy repayment periods can make it difficult to manage education-related debt while meeting other financial goals.
Student loan refinancing may help eligible borrowers replace their existing student loans with a new private loan featuring a different interest rate, repayment term, or monthly payment. Depending on the new offer and the borrower's circumstances, refinancing may reduce interest costs, simplify repayment, or provide more flexibility.
However, refinancing is not suitable for everyone. Borrowers who refinance federal student loans into private loans generally lose access to federal repayment programs, certain forgiveness opportunities, and federal borrower protections.
This guide compares student loan refinancing companies in 2026, explains how refinancing works, and outlines the factors borrowers should consider before making a decision.
What Is Student Loan Refinancing?
Student loan refinancing involves taking out a new private loan to repay one or more existing student loans. The borrower then makes payments to the new lender under the replacement loan's terms.
Depending on the lender and the borrower's qualifications, refinancing may offer:
A lower interest rate
A different monthly payment
A shorter or longer repayment term
One payment instead of several
The possibility of releasing an eligible cosigner
A different fixed or variable interest rate
For example, a borrower with several private student loans may qualify for a new loan with a lower annual percentage rate (APR). If the new loan has favorable terms and fees, the borrower could reduce the overall cost of repayment.
However, a lower monthly payment does not automatically mean savings. Extending the repayment term can increase the total interest paid over time.
The Consumer Financial Protection Bureau explains important differences between student loan refinancing and consolidation, including the potential trade-offs associated with changing repayment terms.
Best Student Loan Refinance Companies in 2026
The following providers are worth comparing when researching student loan refinancing in the United States. Each serves different borrower needs, and the best choice depends on eligibility, loan terms, costs, and customer support.
Rates and lender requirements change frequently. Review current offers directly with each provider before applying.
Company | Potential strength | Best for |
|---|---|---|
Earnest | Customizable repayment options | Borrowers seeking repayment flexibility |
SoFi | Online refinancing and member benefits | Borrowers comparing larger refinance loans |
Splash Financial | Marketplace-style lender comparison | Borrowers wanting to compare offers |
LendKey | Access to participating credit unions and community banks | Borrowers exploring different lending institutions |
ELFI | Personalized customer assistance | Borrowers who value individual guidance |
College Ave | Multiple repayment-term options | Borrowers comparing repayment structures |
Citizens | Banking relationship benefits may be available | Eligible borrowers seeking potential rate discounts |
RISLA | Repayment options and borrower-focused features | Borrowers comparing alternative repayment terms |
These are comparison candidates rather than a universal ranking. Eligibility, state availability, and the final loan offer can affect which lender is most suitable. Current editorial comparisons from NerdWallet and Bankrate can help readers investigate providers further.
1. Earnest
Earnest is a student loan refinancing provider known for customizable repayment options.
Borrowers may want to consider Earnest if they are looking for flexibility when selecting a repayment schedule. The suitability of an offer depends on the borrower's credit profile, income, existing debt, and other eligibility requirements.
Before applying, compare the proposed APR, available repayment terms, fees, and any conditions that apply to payment flexibility.
What to compare:
Fixed and variable interest rate offers
Repayment term options
Eligibility requirements
Cosigner policies
Available hardship assistance
2. SoFi
SoFi offers student loan refinancing for eligible borrowers and provides online account management and member-related benefits.
It may be worth comparing for borrowers who want a digital application process and a range of repayment options.
As with other lenders, the advertised minimum rate is not necessarily the rate every applicant will receive. Review the full offer, including the APR, monthly payment, total interest, and repayment conditions.
What to compare:
Available fixed and variable rates
Autopay discounts, if offered
Loan terms and minimum requirements
Customer support options
Benefits lost when refinancing federal loans
3. Splash Financial
Splash Financial operates as a refinancing marketplace that helps borrowers compare offers from participating lenders.
This approach may be useful for people who want to explore multiple potential loan options without independently researching every participating institution.
Availability and the number of offers depend on the borrower's profile and participating lenders.
What to compare:
The lenders included in the comparison
APR and repayment terms for each offer
Any lender-specific fees
Credit inquiry requirements
Whether the final offer matches the initial estimate
4. LendKey
LendKey connects eligible borrowers with student loan refinancing options through participating credit unions and community banks.
Borrowers who want to compare institutions beyond large national lenders may find this option worth researching.
The final terms depend on the participating lender and the applicant's qualifications. Carefully review the agreement to identify the institution providing the loan and the rules governing repayment.
What to compare:
Available lenders and state eligibility
Fixed and variable interest rates
Repayment terms
Credit score requirements
Available borrower protections
5. ELFI
Education Loan Finance (ELFI) offers student loan refinancing and is an option for borrowers who value personalized assistance during the application process.
Borrowers should evaluate its current interest rates, customer service arrangements, eligibility standards, and repayment terms against competing offers.
Do not choose a lender based on customer service alone. The total cost of the loan and the protections included in the agreement are equally important.
6. College Ave
College Ave offers student loan products, including refinancing options for eligible borrowers.
It may be worth comparing if you want to evaluate different repayment periods and monthly payment structures.
Before accepting an offer, examine the full cost of borrowing. A longer repayment term can make monthly payments more manageable but may increase total interest.
7. Citizens
Citizens offers student loan refinancing options for qualifying borrowers. Depending on the current program and eligibility, certain borrowers may be able to access relationship or autopay discounts.
Compare any available discounts with the lender's standard pricing and check whether you must maintain specific account or payment conditions to qualify.
8. RISLA
The Rhode Island Student Loan Authority (RISLA) is another provider borrowers may wish to investigate when comparing student loan refinancing options.
Review its current availability, interest rates, repayment features, and borrower protections. Confirm whether the program is available in your state and appropriate for your loan type.
Student Loan Refinance Rates in 2026
Student loan refinancing rates depend on the lender, credit history, income, existing obligations, loan amount, repayment term, and whether the borrower selects a fixed or variable rate.
Market comparisons in October 2026 show advertised fixed-rate offers ranging from around 4% to above 10% APR for some providers and borrower profiles. Some lenders advertise higher rates, and not all applicants qualify for the lowest advertised rate.
These figures are broad market examples, not guaranteed offers. Rates and terms may change without notice.
Fixed vs. Variable Interest Rates
Fixed-rate refinancing
A fixed interest rate remains unchanged throughout the agreed repayment period.
Potential advantages include:
Predictable monthly payments
Protection against increases in market interest rates
Easier long-term budgeting
Variable-rate refinancing
A variable rate can rise or fall based on the loan agreement and its reference rate.
Potential advantages may include a lower initial rate in some circumstances. However, payments or total borrowing costs can increase if the rate rises.
Borrowers who prioritize payment certainty may prefer fixed rates. Variable rates require a clear understanding of how often the rate can change, any applicable limits, and the potential effect on monthly payments.
How to Qualify for Student Loan Refinancing
Private lenders generally assess an applicant's ability to repay the new loan.
Requirements vary, but lenders commonly review the following factors.
Credit Score
A stronger credit profile may improve the chances of approval and access to more competitive interest rates. Each lender establishes its own eligibility standards.
Income and Employment
Lenders may evaluate employment, income stability, and the borrower's ability to meet the proposed monthly payment.
Debt-to-Income Ratio
Your debt-to-income ratio compares monthly debt obligations with gross monthly income. A lower ratio may indicate greater repayment capacity, although lender standards differ.
Existing Student Loan Balance
Some lenders impose minimum or maximum refinance amounts. The amount you owe may affect which offers are available.
Education and Graduation Status
Certain lenders require borrowers to have graduated, while others may accept specific applicants who have not completed their degrees. Check the current requirements carefully.
Cosigner or Co-Borrower
A qualified cosigner may help some applicants obtain approval or better terms. However, a cosigner becomes legally responsible for the loan according to the agreement if the borrower does not pay.
Before adding a cosigner, discuss the risks and review the conditions for possible cosigner release.
Benefits of Student Loan Refinancing
Refinancing can be useful when the new loan improves the borrower's financial position.
1. Potential Interest Savings
A lower APR may reduce borrowing costs when the repayment term and fees are taken into account.
2. Simplified Payments
Replacing multiple eligible loans with one new loan can make monthly payments easier to track.
3. Flexible Repayment Terms
Some lenders offer multiple repayment periods, allowing borrowers to compare lower payments with faster repayment.
4. Potential Cosigner Release
Depending on the lender and existing agreement, refinancing may allow a borrower to replace a cosigned loan with a loan in their own name. Approval is not guaranteed.
5. Improved Budget Planning
A suitable fixed-rate loan may help borrowers plan their finances more consistently.
These benefits depend on the actual offer. Refinancing does not automatically reduce the total cost of a student loan.
Risks of Student Loan Refinancing
Before applying, borrowers should consider the potential disadvantages.
Loss of Federal Student Loan Benefits
This is one of the most important considerations. Refinancing federal student loans into a private loan generally eliminates access to federal income-driven repayment plans, federal loan forgiveness programs, and certain federal deferment, forbearance, discharge, and cancellation protections.
Private lenders may offer their own hardship arrangements, but these are not equivalent to federal protections.
Borrowers who may qualify for Public Service Loan Forgiveness or other federal relief should carefully evaluate those benefits before refinancing.
Higher Total Interest Costs
Extending the repayment period can lower the monthly payment while increasing the total interest paid over the life of the loan.
Variable-Rate Increases
A variable interest rate may increase, resulting in higher payments or borrowing costs.
Credit Inquiry and Approval Risks
Depending on the lender and application stage, refinancing may involve credit inquiries. Prequalification may use a soft inquiry, while a full application can require a hard inquiry.
Loss of Existing Loan Features
Some existing loans include benefits or conditions that may not transfer to the replacement loan. Read the current agreement before accepting a new offer.
For more information about federal protections, review the official Federal Student Aid guidance.
Student Loan Refinancing vs. Federal Loan Consolidation
Refinancing and federal consolidation are different processes.
Feature | Private refinancing | Federal Direct Consolidation |
|---|---|---|
Provider | Private lender | U.S. Department of Education |
Main purpose | Replace existing loans with a new private loan | Combine eligible federal loans |
Interest rate | Based on the lender's underwriting and offer | Generally a weighted average of the interest rates on the loans being consolidated, rounded up according to federal rules |
Potential for lower interest rate | Possible, depending on the offer | Generally does not lower the underlying interest rate |
Federal borrower protections | Lost for federal loans refinanced into private debt | Generally retains federal loan status, though specific benefits and repayment consequences can vary |
Credit approval | Private lender requirements apply | Different eligibility process |
Federal consolidation may simplify repayment for some borrowers, but it is not the same as obtaining a lower-rate private refinance loan. Borrowers should review the consequences of both options before deciding.
Example: How Refinancing May Affect Your Payments
Consider a hypothetical borrower with $40,000 in student loan debt.
Suppose the borrower has an existing loan with a 7% fixed interest rate and ten years remaining. They receive a new refinance offer with a 5% fixed rate and the same ten-year repayment term, with no additional fees.
Under these simplified assumptions:
Item | Existing loan | Refinance loan |
|---|---|---|
Starting balance | $40,000 | $40,000 |
Interest rate | 7% fixed | 5% fixed |
Repayment term | 10 years | 10 years |
Estimated monthly payment | $464 | $424 |
Estimated total payments | $55,680 | $50,880 |
The illustrative difference is approximately $40 per month and $4,800 over the repayment period.
Actual payment amounts may vary because of payment timing, compounding conventions, fees, and lender terms. This example does not represent an actual lender offer and excludes any fees or other costs.
If refinancing involves extending the repayment term, the monthly payment could fall further while the total amount paid over time increases.
How to Refinance Student Loans Step by Step
Step 1: Review Your Existing Loans
List each loan's current balance, interest rate, monthly payment, repayment term, and whether it is federal or private.
Step 2: Check Your Credit and Income
Review your credit reports and estimate your monthly budget. Correct any reporting errors before applying when possible.
Step 3: Compare Multiple Lenders
Request offers from several lenders. Compare APRs, repayment periods, fees, eligibility, and hardship provisions rather than looking only at the advertised rate.
Step 4: Prequalify Where Available
Some lenders allow borrowers to check estimated offers using a soft credit inquiry. Confirm whether prequalification affects your credit score.
Step 5: Calculate the Total Cost
Compare the total amount payable over the life of each loan. Include any fees and consider the effect of changing the repayment period.
Step 6: Review Federal Loan Protections
If any of your loans are federal, carefully assess the consequences of replacing them with private debt before proceeding.
Step 7: Submit the Application
If the offer meets your needs, provide the required documents and review the final approval terms.
Step 8: Confirm the Old Loans Are Paid
After the refinance closes, confirm that the new lender has paid the appropriate existing loan balances. Continue making required payments until each original servicer confirms the account is paid off.
Tips for Getting Better Student Loan Refinance Offers
Check your credit reports for errors before applying.
Compare several lenders instead of accepting the first offer.
Consider fixed rates if predictable payments are important.
Choose the shortest repayment term you can comfortably afford if your goal is minimizing interest.
Review all fees and discounts carefully.
Avoid extending the term solely to lower the monthly payment without calculating the total cost.
Compare lender hardship policies and cosigner release conditions.
Keep federal loans separate if federal repayment or forgiveness protections may be valuable to you.
Frequently Asked Questions
Is student loan refinancing worth it in 2026?
It may be worthwhile if you qualify for a better rate or more suitable repayment terms and the overall benefits outweigh the costs. Borrowers with federal loans must also consider the loss of federal protections before refinancing into private debt.
What credit score do I need to refinance student loans?
Requirements vary by lender. Some lenders publish minimum credit scores, while others consider a broader combination of credit history, income, debt, and other factors. A cosigner may help some applicants qualify.
Can I refinance both federal and private student loans?
Private lenders may allow eligible borrowers to refinance both types into one private loan. However, federal loans converted into private debt lose federal borrower protections and program eligibility.
Can I refinance student loans without a degree?
Some lenders may consider applicants who did not graduate, while others require a completed degree. Check the lender's current eligibility rules.
Does refinancing student loans hurt my credit?
Prequalification may involve a soft inquiry that does not affect your credit score. A full application may require a hard inquiry. The longer-term effect also depends on account changes, payment history, and your overall credit profile.
Can I refinance student loans more than once?
In many cases, borrowers can refinance again if they qualify and the new terms make financial sense. Compare the costs and benefits each time, and do not assume that future offers will be available.
Should I choose a fixed or variable student loan refinance rate?
A fixed rate offers predictable interest costs, while a variable rate can rise or fall. Compare the initial APR, possible future rate changes, payment affordability, and total cost.
Can refinancing lower my monthly payment?
Yes, depending on the new interest rate and repayment term. However, a lower monthly payment may result from extending the repayment period, which can increase total interest costs.
What is the difference between student loan refinancing and consolidation?
Private refinancing replaces existing debt with a new private loan, potentially changing the rate and repayment terms. Federal Direct Consolidation combines eligible federal loans under federal rules and generally does not reduce the underlying interest rate.
Final Thoughts
Student loan refinancing can be a useful financial strategy for eligible borrowers who want to reduce interest costs, simplify payments, or choose a different repayment schedule. Providers such as Earnest, SoFi, Splash Financial, LendKey, ELFI, College Ave, Citizens, and RISLA offer options worth comparing.
The right choice depends on your credit profile, income, existing loan terms, and financial priorities. Compare the APR, fees, repayment period, and total amount payable before accepting an offer.
Most importantly, understand the consequences of refinancing federal student loans into private debt. Losing federal repayment, forgiveness, and hardship protections can outweigh potential interest savings for some borrowers.
Disclaimer: This article is for informational and educational purposes only and does not constitute financial, legal, or tax advice. Rates, eligibility requirements, lender offerings, and repayment terms may change. Verify current information with lenders and consult a qualified financial professional when appropriate.