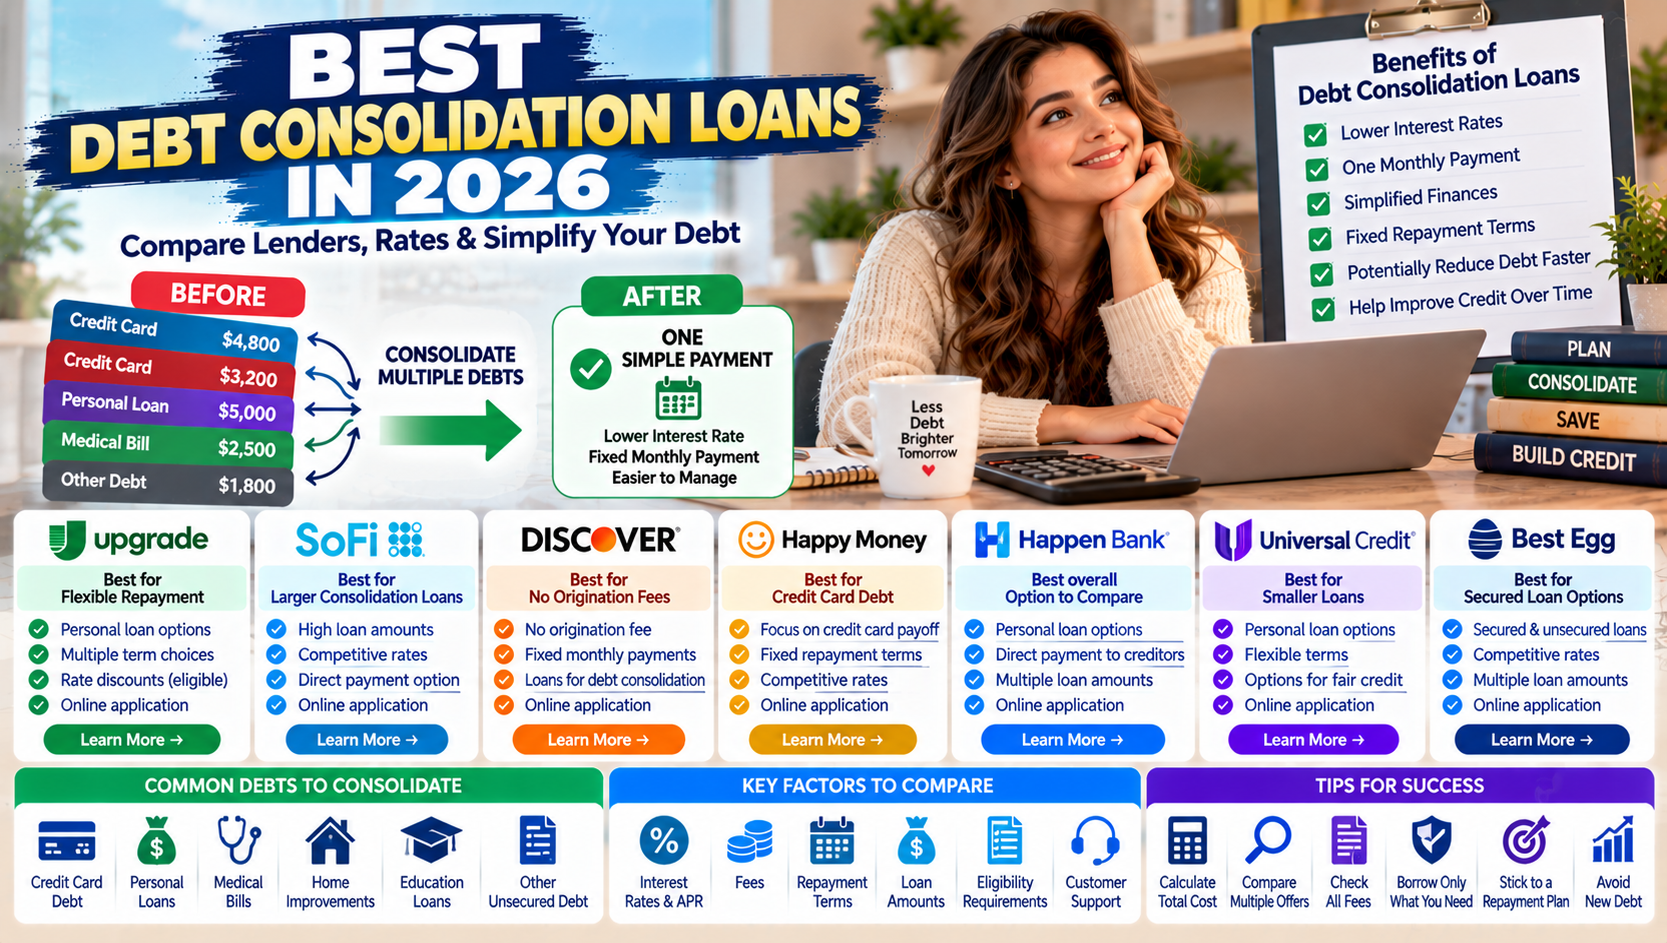
Managing several credit card balances, personal loans, and other debts can make monthly budgeting difficult. Different due dates, interest rates, and minimum payments may increase financial pressure and make it harder to track your progress.
A debt consolidation loan may help simplify repayment by combining eligible debts into one new loan with a single scheduled payment. If you qualify for a lower annual percentage rate (APR), you may also reduce borrowing costs. However, consolidation does not automatically save money, and a longer repayment period can increase the total interest you pay.
In this guide, we compare some of the best debt consolidation loans in 2026, explain how they work, and show you how to evaluate lenders, fees, eligibility requirements, and potential savings before applying.
Best Debt Consolidation Loans in 2026: Top Lenders
Different lenders serve different borrowers. Some focus on applicants with strong credit, while others offer options for borrowers with fair credit, joint applications, or secured loans.
Lender | Best For | Key Consideration |
|---|---|---|
Upgrade | Flexible repayment options | Origination fees and multiple rate discounts |
SoFi | Larger consolidation loans | Strong-credit borrowers may receive better offers |
Discover | No origination fee | Eligibility requirements and minimum loan amount |
Happy Money | Credit card debt consolidation | Primarily designed for credit card payoff |
Happen Bank (formerly LendingClub) | Overall consolidation option to compare | Review current rates, fees, and eligibility |
Universal Credit | Smaller loan amounts | Compare APR and upfront fees |
Best Egg | Secured loan options | Collateral requirements and repayment risk |
These are lenders worth comparing, not guarantees of approval or the lowest available rates. Product availability and terms can change. Check the latest offer directly with each lender before making a decision.
Recent lender comparisons from NerdWallet and CNBC Select identify several of these companies for different consolidation needs. <Cite refs={["turn894957search0","turn894957search3"]}/>
1. Upgrade — Best for Flexible Repayment Options
Upgrade offers personal loans that eligible borrowers can use to consolidate certain debts. Depending on the offer, borrowers may have different repayment terms and could qualify for discounts.
Potential Benefits
Personal loan options for debt consolidation.
Multiple repayment-term choices.
Potential discounts for eligible borrowers.
Direct payment to eligible creditors through supported features.
Online prequalification options.
What to Consider
Upgrade may charge an origination fee, which can reduce the amount you receive. Compare the APR, total repayment amount, and payment schedule with your existing debts.
Best for: Borrowers who want to compare flexible personal loan terms and consolidation features.
Official website: https://www.upgrade.com/
2. SoFi — Best for Larger Consolidation Loans
SoFi offers personal loans that qualifying borrowers can use to consolidate debt. Its larger loan limits may suit borrowers with substantial eligible balances.
Potential Benefits
Personal loans for larger borrowing needs.
Online application and account management.
Potential rate discounts for eligible borrowers.
Options for direct payment to eligible creditors.
What to Consider
Approval and pricing depend on your financial profile. Borrowers with weaker credit may not qualify for the most competitive rates, and the approved amount may be lower than requested.
Best for: Borrowers with suitable credit and income who need to consolidate larger balances.
Official website: https://www.sofi.com/personal-loans/
3. Discover — Best for No Origination Fees
Discover offers personal loans without an origination fee, according to its published personal loan information. This can make it worth comparing for borrowers who want to avoid an upfront processing charge.
Potential Benefits
No origination fee on its personal loan product.
Fixed repayment schedule.
Online loan management.
Direct payment to eligible creditors may be available.
What to Consider
A loan without an origination fee is not necessarily the cheapest overall. Compare the APR, repayment term, minimum borrowing amount, and total interest against competing offers.
Best for: Eligible borrowers seeking a consolidation loan without an origination fee.
Official website: https://www.discover.com/personal-loans/
4. Happy Money — Best for Credit Card Debt Consolidation
Happy Money offers personal loans designed primarily for credit card debt consolidation. This may be relevant to borrowers who want to replace multiple eligible credit card balances with one installment loan.
Potential Benefits
A focus on credit card debt payoff.
Fixed monthly payments for qualifying loans.
Online application process.
An option to compare against general-purpose personal loans.
What to Consider
Check the loan's APR, fees, eligible debt types, and minimum loan amount. Consolidation makes sense only if the new terms support your repayment goals.
Best for: Borrowers seeking to consolidate eligible credit card balances.
Official website: https://www.happymoney.com/
5. Happen Bank — Best Overall Option to Compare
Happen Bank, formerly LendingClub, offers personal loan products that can be used for eligible debt consolidation. It is worth comparing when looking for a lender that may simplify the payoff process.
Potential Benefits
Personal loan options for eligible borrowers.
Potential direct payment to creditors.
Online application and account tools.
An alternative to compare with other consolidation lenders.
What to Consider
Review current eligibility rules, origination fees, repayment terms, and total borrowing costs. Confirm the lender's current brand name and loan terms when applying.
Best for: Borrowers who want to compare a consolidation-focused personal loan option.
Official website: https://www.happenbank.com/
6. Universal Credit — Best for Smaller Consolidation Loans
Universal Credit offers personal loans to qualifying borrowers and may be useful when comparing offers for smaller borrowing needs.
Potential Benefits
Online application options.
Personal loans for eligible expenses.
An option to compare for imperfect credit.
Potential discounts under qualifying loan terms.
What to Consider
Origination fees and interest rates can substantially affect the amount you receive and the total you repay. Read the loan agreement carefully and confirm that the approved amount will cover the debts you intend to consolidate.
Best for: Borrowers comparing smaller personal loan offers.
Official website: https://www.universal-credit.com/
7. Best Egg — Best for Comparing Secured Loans
Best Egg offers personal loans, including secured options for eligible borrowers. A secured loan uses an eligible asset as collateral and may have different eligibility and pricing requirements from an unsecured loan.
Potential Benefits
Secured and unsecured personal loan options, depending on eligibility.
Online application tools.
An alternative for borrowers comparing consolidation products.
Potential financing for eligible debt payoff needs.
What to Consider
A secured loan puts the pledged asset at risk if you fail to repay. Carefully compare the interest rate, fees, collateral terms, and consequences of missed payments before proceeding.
Best for: Borrowers who qualify for a secured option and understand the risks.
Official website: https://www.bestegg.com/
What Is a Debt Consolidation Loan?
A debt consolidation loan is a new loan used to repay multiple existing debts. Instead of managing several balances and payment dates, you make payments toward one new loan under its repayment agreement.
For example, you might use a personal loan to pay off three credit card balances. After the creditors receive payment, you repay the new loan through scheduled installments.
Debt consolidation can potentially help you:
Simplify monthly bill payments.
Replace high-interest debt with a lower-rate loan.
Set a defined repayment schedule.
Understand when the loan is expected to be paid off.
Reduce interest costs if the new terms are more favorable.
However, consolidation does not erase debt. You still owe the amount borrowed, and the new loan may cost more if its fees or interest rate are high.
Types of Debt Consolidation Options
1. Personal Loan for Debt Consolidation
A personal loan provides a lump sum that you use to repay eligible debts. Many personal loans have fixed interest rates and scheduled monthly payments.
This option may be useful when the APR is lower than the rates on the debts being repaid.
2. Balance Transfer Credit Card
A balance transfer credit card allows eligible borrowers to move existing credit card balances to a new card. Some cards offer a promotional 0% APR period, although balance transfer fees may apply.
This option can be attractive for borrowers with good credit who can repay the balance before the promotional period ends. Any remaining balance may be subject to the card's regular APR.
3. Home Equity Loan
A home equity loan lets eligible homeowners borrow against the equity in their property. It may offer different rates and repayment terms from an unsecured personal loan.
However, the home is generally collateral. If you cannot repay the loan, you risk losing the property through foreclosure.
4. Home Equity Line of Credit (HELOC)
A HELOC is a revolving credit line secured by home equity. It can provide flexibility, but interest rates may be variable and repayment structures can change over time.
Using home equity to repay unsecured debt converts that debt into borrowing secured by your home, increasing the potential consequences of missed payments.
5. Debt Management Plan
A nonprofit credit counseling agency may help eligible borrowers organize repayment through a debt management plan. The agency may work with creditors on payment arrangements or interest concessions.
A debt management plan is not a new consolidation loan, and fees or eligibility conditions may apply.
How to Choose the Best Debt Consolidation Loan
Compare APRs
APR includes the interest rate and certain fees, giving you a broader measure of borrowing costs than the interest rate alone.
Compare offers for similar loan amounts and repayment terms. A lower APR can help, but also consider the total interest paid and how long repayment will take.
Review Origination Fees
Some lenders deduct an origination fee from the loan proceeds. For example, a 5% fee on a $10,000 loan equals $500.
You could receive only $9,500 while still owing the full $10,000 principal. Confirm whether the loan will provide enough money to pay the intended creditors.
Check Repayment Terms
Longer repayment terms often reduce the monthly payment but can increase the total interest paid.
Choose a term that balances affordability with your goal of becoming debt-free. Avoid extending repayment unnecessarily just to make the monthly payment smaller.
Look for Direct Creditor Payments
Some lenders can send the loan proceeds directly to eligible creditors. This can simplify the process and reduce the temptation to use the money for other expenses.
Confirm which creditors qualify and whether direct payment affects your rate or fees.
Check Credit Requirements
Lenders evaluate factors such as credit score, credit history, income, existing debt, and repayment capacity. Prequalification may help you compare offers before submitting a full application.
Avoid Unnecessary Borrowing
Borrow only enough to cover the debts you intend to consolidate and any justified fees. A larger loan creates a larger repayment obligation.
Example: Calculating Potential Savings
Suppose you have $10,000 in credit card debt at a 25% APR and are considering a personal loan with a 15% APR.
The new loan may reduce borrowing costs, but the actual savings depend on fees, repayment terms, payment timing, and how quickly the balance is repaid.
Item | Existing Debt | Example New Loan |
|---|---|---|
Starting balance | $10,000 | $10,000 |
Annual interest rate | 25% APR | 15% APR |
Repayment structure | Credit card payments | Fixed installment payments |
Potential benefit | Existing payment flexibility | Lower rate and defined schedule, if approved |
This comparison is illustrative, not a savings guarantee. The APR on your actual offer may differ, and origination fees can reduce the benefit.
Before consolidating, calculate the total repayment amount for each option. If the new loan extends repayment over a longer period, you could pay more overall despite a lower monthly payment.
How to Apply for a Debt Consolidation Loan
List all your debts. Record each balance, APR, minimum payment, and due date.
Calculate the amount required. Include only eligible debts you intend to repay with the new loan.
Review your credit profile. Check your credit reports for errors and assess your current financial position.
Compare multiple lenders. Review APRs, fees, loan terms, and direct-pay options.
Prequalify where available. Some lenders offer prequalification through a soft credit inquiry that generally does not affect your score.
Prepare your documents. You may need identification, income information, bank statements, and details of existing debts.
Review the final agreement. Confirm the amount received, fees, monthly payment, APR, and total repayment.
Pay off the intended debts. If the lender does not pay creditors directly, follow the loan agreement and verify that the old balances are cleared.
Avoid rebuilding the balances. Adjust your spending and repayment habits so that paid-off credit cards do not accumulate new debt.
Pros and Cons of Debt Consolidation
Potential Advantages | Potential Disadvantages |
|---|---|
One scheduled payment | New loan fees may apply |
Potentially lower interest costs | Approval is not guaranteed |
Defined repayment period | Longer terms may increase total interest |
Easier payment tracking | A new application may trigger a hard inquiry |
May support credit improvement over time | New debt can worsen finances if spending continues |
Debt consolidation works best when the new loan is affordable and accompanied by a realistic plan to avoid accumulating additional high-interest debt.
Common Debt Consolidation Mistakes to Avoid
Choosing a Loan Only for Its Monthly Payment
A lower payment may result from extending the repayment term rather than reducing the overall cost. Compare the total amount you will repay.
Ignoring Fees
Origination fees and other charges can reduce savings. Include all applicable costs when comparing offers.
Continuing to Use Paid-Off Credit Cards
If you consolidate credit card debt but continue making purchases you cannot afford, you may end up with both the new loan and new card balances.
Borrowing Against Your Home Without Considering the Risk
Home equity borrowing can offer different rates, but it places your home at risk if you cannot repay. Consider this carefully before using a secured option to pay unsecured debt.
Applying to Too Many Lenders Without a Plan
Compare lenders strategically and use prequalification where available. Confirm whether a lender performs a soft or hard credit inquiry before applying.
Frequently Asked Questions
What is the best debt consolidation loan in 2026?
The best loan depends on your credit profile, balance, income, and repayment needs. Upgrade, SoFi, Discover, Happy Money, Happen Bank, Universal Credit, and Best Egg are options to compare, but the most suitable offer varies by borrower.
Does debt consolidation hurt your credit score?
Applying for a loan may lead to a hard inquiry, which can temporarily affect your score. Opening a new account also changes your credit profile. Over time, consistent payments and lower credit card utilization may help, but results are not guaranteed.
Can I get a debt consolidation loan with bad credit?
Some lenders consider applicants with fair or imperfect credit. However, they may offer higher APRs or lower loan amounts. Compare the total borrowing cost and consider nonprofit credit counseling if loan offers are too expensive.
How much can I borrow for debt consolidation?
Loan amounts depend on the lender and your financial circumstances. Some lenders offer smaller loans, while others provide amounts of tens of thousands of dollars or more to eligible borrowers.
Is debt consolidation better than a balance transfer card?
It depends on your credit, debt amount, fees, and repayment plan. A balance transfer card may be useful if you qualify for a promotional APR and can repay the balance within the promotional period. A personal loan may offer a fixed repayment schedule.
Can debt consolidation reduce my monthly payment?
It may reduce your monthly payment if the new loan has a lower rate, a longer term, or both. However, a longer term may increase the total interest paid. Compare both monthly affordability and overall cost.
How long does debt consolidation take?
The timeline varies by lender, application verification, and whether funds are paid directly to creditors. Some loans can be funded quickly after approval, while others take longer. Confirm the current timeline with the lender.
Is debt consolidation the same as debt settlement?
No. Debt consolidation replaces multiple debts with a new loan or payment arrangement. Debt settlement generally involves attempting to settle debts for less than the amount owed and can carry significant credit, fee, and tax risks.
Final Thoughts
The best debt consolidation loans in 2026 can help eligible borrowers simplify payments and potentially reduce interest costs. Upgrade, SoFi, Discover, Happy Money, Happen Bank, Universal Credit, and Best Egg offer options worth comparing for different borrowing needs.
Before choosing a lender, compare APRs, origination fees, repayment periods, and the total amount you will repay. Consider whether direct creditor payments or a nonprofit debt management plan could be appropriate for your situation.
The goal is not simply to combine debts into one payment. It is to create a realistic repayment plan that reduces costs where possible and helps you avoid taking on more debt.