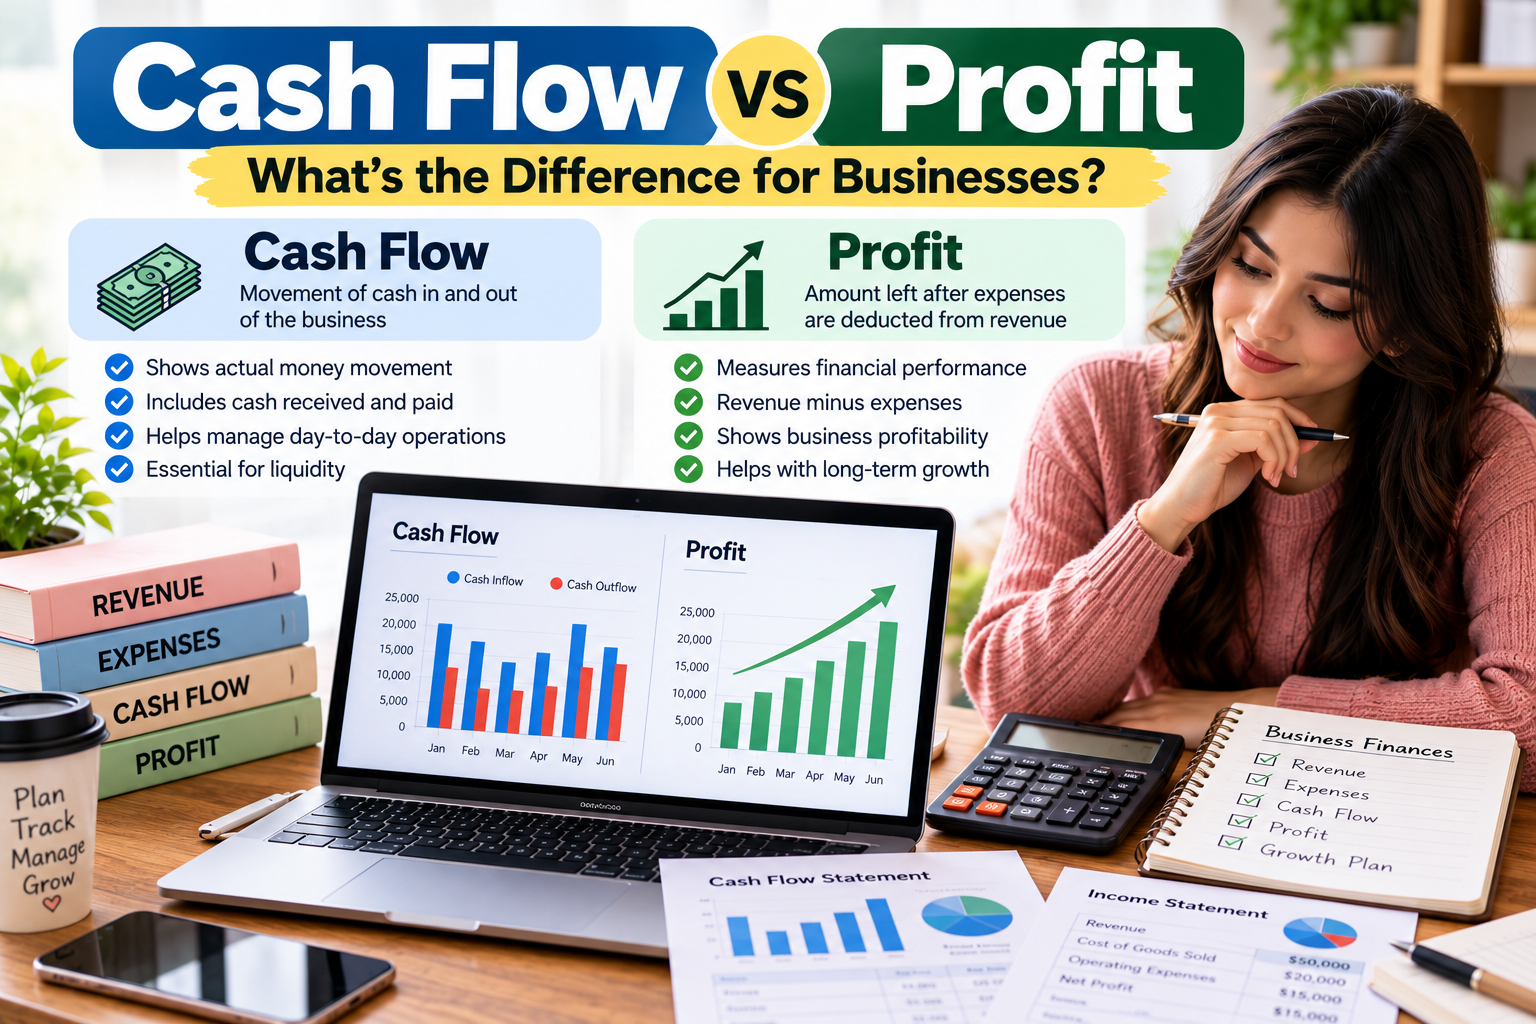
Many business owners assume that making a profit means they have enough money available to pay their bills. However, profit and cash flow measure two different aspects of financial performance.
A business can report a profit and still struggle to pay suppliers, employees, rent, or loan installments. Similarly, a business may receive a large amount of cash during a particular month without generating a profit.
Understanding the difference between cash flow and profit is essential for managing business finances, planning investments, and making informed decisions about growth.
For example, imagine a company sells $20,000 worth of products in March but allows customers to pay their invoices in April. The company may record revenue and profit in March, depending on its accounting method, even though it has not yet collected the money.
If the company must pay suppliers in March, it could experience a cash shortage despite reporting a profit.
This guide explains cash flow vs. profit, how each is calculated, why they matter, and how businesses can improve both financial measures.
What Is Profit?
Profit is the amount remaining after a business subtracts the relevant costs and expenses from its revenue.
It measures financial performance over a specific period, such as a month, quarter, or year.
A business earns a profit when its relevant revenue exceeds the expenses included in the calculation. When expenses exceed revenue, the business records a loss.
The Basic Profit Formula
Profit = Revenue − Expenses
Suppose a business generates $50,000 in revenue during one month and incurs $35,000 in relevant expenses.
Profit = $50,000 − $35,000 = $15,000.
The business earns $15,000 in profit under the assumptions in this example.
However, the exact profit figure depends on which expenses are included. Gross profit, operating profit, and net profit provide different views of business performance.
Types of Profit
Gross profit: Revenue minus the cost of goods sold. It helps businesses evaluate the relationship between sales and direct product or service costs.
Operating profit: Profit remaining after operating expenses are deducted from gross profit. It helps measure the performance of the company's core operations.
Net profit: The amount remaining after the expenses included in net income have been deducted, including applicable interest and taxes.
Net profit is often used to evaluate overall profitability, although it does not tell you how much cash the business has available.
Why Profit Matters
Profit helps business owners evaluate whether their business model is financially sustainable.
It can help them assess pricing, control costs, compare performance across periods, and decide whether to expand operations.
Investors and lenders may also review profitability when evaluating a company's financial condition.
However, profit alone does not show whether the business can meet its immediate payment obligations.
What Is Cash Flow?
Cash flow refers to the movement of money into and out of a business during a specific period.
Cash inflows may include customer payments, cash sales, loan proceeds, or money received from investors.
Cash outflows may include supplier payments, wages, rent, taxes, equipment purchases, and loan repayments.
When cash inflows exceed cash outflows during a period, the business has positive net cash flow for that period. When outflows exceed inflows, it has negative net cash flow.
The Basic Cash Flow Formula
Net Cash Flow = Total Cash Inflows − Total Cash Outflows
Suppose a company receives $25,000 in cash during April and pays $21,000 in cash expenses and other obligations.
Net cash flow = $25,000 − $21,000 = $4,000.
The company has positive net cash flow of $4,000 for April.
This does not necessarily mean that it earned $4,000 in profit. Some cash inflows may come from borrowing or investment, while some cash outflows may involve purchasing equipment or repaying loan principal.
Why Cash Flow Matters
Cash flow determines whether a business has enough available money to meet its financial obligations when payments are due.
A business needs cash to pay employees, purchase inventory, cover rent, pay suppliers, and handle unexpected expenses.
Even a profitable company can face financial difficulties if customers pay late or too much money is tied up in inventory.
Monitoring cash flow helps businesses identify potential shortages before they become serious problems.
Cash Flow vs. Profit: Key Differences
Although cash flow and profit are related, they measure different things.
Feature | Profit | Cash Flow |
|---|---|---|
What it measures | Financial performance | Movement of cash |
Main calculation | Revenue minus relevant expenses | Cash inflows minus cash outflows |
Timing | Follows applicable accounting rules | Reflects when cash is received or paid |
Includes credit sales before collection? | Generally, under accrual accounting | No, not until cash is collected |
Includes loan proceeds? | Not as profit | Yes, as a financing cash inflow |
Includes loan principal repayment? | Generally not an expense | Yes, as a cash outflow |
Main purpose | Assess profitability | Assess liquidity and payment capacity |
The distinction becomes clearer when you examine actual business situations.
Can a Business Be Profitable but Have Negative Cash Flow?
Yes. A business can report a profit while experiencing negative cash flow.
This often happens when revenue is recognized before customers pay their invoices.
Example: A Business With Delayed Customer Payments
Suppose a company sells $30,000 worth of products in May.
Its accounting records show:
Revenue: $30,000.
Cost of goods sold and other expenses: $22,000.
Profit: $8,000.
However, customers have only paid $10,000 by the end of May.
During the same month, the company pays $18,000 to suppliers, employees, and other parties.
Its cash movement from these transactions is:
Cash received − Cash paid = $10,000 − $18,000 = −$8,000.
The company has an $8,000 cash outflow on a net basis from these transactions, even though it reports $8,000 in profit.
The unpaid customer invoices may eventually be collected, but the business must still cover its current obligations.
This example illustrates why business owners should monitor accounts receivable, payment deadlines, and available cash alongside profit.
Other reasons for negative cash flow despite profitability may include purchasing inventory, paying down loan principal, buying equipment, or making large upfront investments.
Can a Business Have Positive Cash Flow but Be Unprofitable?
Yes. Positive cash flow does not automatically mean a company is profitable.
A business may receive cash from borrowing, selling assets, or obtaining investment funding without generating sufficient profit from its operations.
Example: Positive Cash Flow From Borrowing
Suppose a new business receives $50,000 from a bank loan.
It spends $35,000 on equipment, inventory, and operating payments during the period.
Its net cash movement from these transactions is positive $15,000.
However, the loan proceeds are not business revenue, and the equipment purchase may be recorded as an asset rather than an immediate expense in full.
If the business's revenue is insufficient to cover its recognized expenses, it may still report a loss.
The business has additional cash available, but it also has a debt obligation.
This is why cash flow should be evaluated alongside profitability, liabilities, and the source of cash inflows.
How Accounting Methods Affect Profit and Cash Flow
The accounting method used by a business influences when revenue and expenses are recognized.
Understanding this distinction helps explain why profit and cash flow figures may differ.
Accrual Accounting
Under accrual accounting, revenue is generally recognized when it is earned and expenses when they are incurred, subject to the applicable accounting standards.
Payment may occur before or after recognition.
For example, a company may deliver a product and issue an invoice in June but receive payment in July. Under the relevant accounting rules, revenue may be recognized in June even though the cash arrives in July.
Similarly, a business may recognize an expense before paying the related invoice.
This method provides a more complete view of financial performance for many businesses.
Cash-Basis Accounting
Under cash-basis accounting, income and expenses are generally recorded when cash is received or paid, subject to the applicable rules and exceptions.
This approach may be simpler for some small businesses, but eligibility and requirements depend on the jurisdiction and circumstances.
Cash-basis profit is not identical to a complete cash flow analysis because financing transactions and asset purchases may require separate treatment.
Businesses should follow the accounting and tax rules that apply to their situation.
Understanding the Three Sections of a Cash Flow Statement
A cash flow statement explains how a company's cash balance changes during a reporting period.
It generally divides cash movements into three categories.
1. Operating Activities
Operating cash flow relates to the company's main business activities.
Examples include cash collected from customers and payments made to suppliers, employees, and other operating service providers.
Positive operating cash flow can indicate that the core business is generating cash, although the figure should be evaluated over time and in context.
2. Investing Activities
Investing cash flow includes transactions involving long-term assets and investments.
Examples include buying equipment, purchasing property, or selling business assets.
A negative investing cash flow is not necessarily a problem. It may reflect investment in future capacity, provided the spending is appropriate and financially sustainable.
3. Financing Activities
Financing cash flow includes transactions involving borrowing, repayment of loan principal, issuing shares, or paying dividends.
For example, a bank loan increases cash when the funds are received, while repayment of principal reduces cash.
These transactions can significantly affect the cash balance without directly representing operating profit.
Reviewing all three sections provides a more complete understanding of why the company's cash position changed.
How to Improve Cash Flow Without Sacrificing Profitability
Businesses should aim to manage both profitability and liquidity.
Improving cash flow does not always require increasing revenue. Better payment practices, inventory management, and spending decisions may also help.
1. Collect Customer Payments Faster
Late payments can create cash shortages, especially for businesses that sell on credit.
Use clear payment terms, issue invoices promptly, and follow up on overdue balances professionally.
Where appropriate, consider deposits, milestone payments, or shorter payment terms for new customers.
Make sure your policies comply with relevant contracts and laws.
2. Manage Inventory Carefully
Excess inventory ties up money that could otherwise be used for business operations.
Review sales patterns, supplier lead times, and reorder points before purchasing additional stock.
However, keeping too little inventory can cause stockouts and lost sales. The goal is to maintain an appropriate balance between availability and cash efficiency.
3. Forecast Upcoming Cash Needs
Prepare a cash flow forecast that estimates receipts and payments over the coming weeks or months.
Include expected customer payments, payroll, supplier invoices, rent, taxes, debt payments, and planned purchases.
Compare the forecast with your current cash balance to identify periods when funds may be insufficient.
Update the forecast when customer payment dates or major expenses change.
4. Review Expenses Regularly
Examine recurring costs such as subscriptions, insurance, shipping contracts, and supplier agreements.
Identify expenses that no longer provide sufficient value and investigate whether better terms are available.
Avoid cutting essential spending without considering the effect on customer experience, product quality, or future revenue.
5. Improve Pricing and Product Profitability
Review product prices and the complete cost of fulfilling each sale.
A product that generates strong revenue may contribute relatively little profit if its sourcing, shipping, returns, and advertising costs are high.
Analyze margins by product or service to identify where pricing or cost adjustments may be appropriate.
6. Plan Capital Purchases Carefully
Large equipment purchases can reduce available cash even if the asset is not immediately expensed in full for accounting purposes.
Before making a major purchase, evaluate the expected benefits, cash requirements, financing options, and effect on future operations.
Consider whether the purchase is necessary now or can be scheduled for a period when cash availability is stronger.
7. Maintain an Appropriate Cash Reserve
A reserve can help cover unexpected expenses or temporary reductions in customer receipts.
The appropriate amount depends on the business's operating costs, revenue stability, payment obligations, and access to financing.
A reserve should be based on the company's actual risks rather than an arbitrary target.
How to Measure Profitability and Cash Flow Together
The most useful financial analysis combines profitability measures with cash flow information.
Net Profit Margin
Net profit margin shows how much net profit a business generates from its revenue.
Net Profit Margin = (Net Profit ÷ Revenue) × 100
If a business earns $12,000 in net profit from $100,000 in revenue, its net profit margin is 12%.
This helps evaluate profitability but does not show when customers pay or when bills are due.
Operating Cash Flow
Operating cash flow measures the cash generated or used by the company's operating activities, using the applicable cash flow reporting method.
Positive operating cash flow over time can indicate that the core business is generating cash, but unusual timing effects and working capital changes should also be considered.
Free Cash Flow
Free cash flow is commonly calculated as operating cash flow minus capital expenditures.
Free Cash Flow = Operating Cash Flow − Capital Expenditures
Suppose a company generates $40,000 in operating cash flow and spends $12,000 on capital expenditures.
Free cash flow = $40,000 − $12,000 = $28,000.
The company has $28,000 in free cash flow under this simplified calculation.
This measure can help assess the cash remaining after certain investments, although definitions may vary and it should not be confused with net profit.
Working Capital
Working capital is generally calculated as current assets minus current liabilities.
It helps assess short-term financial flexibility, although the amount of working capital alone does not guarantee that sufficient cash is available on a particular payment date.
Reviewing these measures together gives business owners a more balanced view of financial health.
Common Mistakes Businesses Make When Comparing Cash Flow and Profit
Mistake 1: Assuming Revenue Means Cash Received
A sale made on credit may increase revenue before the customer pays.
Track outstanding invoices and expected collection dates rather than assuming all recorded sales are available as cash.
Mistake 2: Treating Loan Proceeds as Profit
Borrowing increases cash but also creates a liability.
Separate financing transactions from business revenue when evaluating profitability.
Mistake 3: Ignoring Inventory and Equipment Purchases
Buying inventory or equipment may use cash before the related products generate revenue.
Understand how these purchases affect cash flow and how they are treated in the financial statements.
Mistake 4: Focusing Only on Monthly Profit
A monthly profit figure does not necessarily reveal whether cash will be available for upcoming obligations.
Use a cash flow forecast to understand the timing of receipts and payments.
Mistake 5: Assuming Positive Cash Flow Always Indicates Success
Positive cash flow may result from borrowing, investment, or selling assets rather than profitable operations.
Review the source of cash inflows and evaluate operating performance separately.
Conclusion
Cash flow and profit are both essential measures of business financial health, but they answer different questions.
Profit shows how much a business earns after the relevant expenses are deducted. Cash flow shows how money moves into and out of the business.
A company can be profitable while struggling to pay its bills, or it can have positive cash flow because of borrowing while operating at a loss.
Business owners should therefore monitor financial statements, customer payments, expenses, inventory, debt obligations, and cash forecasts together.
By improving collection practices, controlling costs, planning purchases, and reviewing financial performance regularly, businesses can make better decisions and reduce the risk of unexpected cash shortages.
The objective is not simply to increase profit or maintain a high cash balance. It is to build a business that generates sustainable earnings while maintaining the liquidity needed to operate reliably.
Frequently Asked Questions (FAQs)
1. What is the difference between cash flow and profit?
Profit measures the amount remaining after relevant expenses are deducted from revenue. Cash flow measures the movement of cash into and out of a business during a specific period.
2. Can a business be profitable but have negative cash flow?
Yes. A business may record revenue before customers pay their invoices, purchase inventory, invest in equipment, or repay loan principal. These activities can reduce available cash even when the business reports a profit.
3. Can a business have positive cash flow but make a loss?
Yes. A business may receive cash from loans, investors, or asset sales while its operating expenses exceed its revenue. Positive cash flow does not automatically mean the business is profitable.
4. Which is more important: cash flow or profit?
Both matter. Profitability helps evaluate whether the business model generates earnings, while cash flow helps determine whether the company can meet payment obligations when they are due.
5. How do you calculate profit?
A simplified formula is profit equals revenue minus the relevant expenses. The result depends on whether you are calculating gross profit, operating profit, or net profit.
6. How do you calculate net cash flow?
Subtract total cash outflows from total cash inflows for the period.
Formula: Net Cash Flow = Total Cash Inflows − Total Cash Outflows.
7. What is operating cash flow?
Operating cash flow measures cash generated or used by a company's main business activities, including relevant receipts from customers and payments to suppliers, employees, and other operating parties.
8. What is free cash flow?
Free cash flow is commonly calculated by subtracting capital expenditures from operating cash flow. It helps estimate the cash remaining after certain investments in long-term assets.
9. How can a profitable business run out of cash?
A profitable business may run out of cash if customers pay late, inventory absorbs too much money, large bills fall due, or the company makes significant investments without sufficient liquidity planning.
10. How can a small business improve cash flow?
A small business can improve cash flow by collecting payments faster, managing inventory carefully, forecasting expenses, reviewing supplier terms, controlling unnecessary costs, and maintaining an appropriate cash reserve.
11. Does taking out a loan increase profit?
No. Loan proceeds generally increase cash and liabilities rather than revenue or profit. Interest expense may affect profit, while repayment of loan principal generally reduces cash and the outstanding debt.
12. Why should businesses prepare a cash flow forecast?
A cash flow forecast helps estimate when money will enter and leave the business. It can identify potential shortages early and help owners plan payments, financing, and purchases.
13. Is cash flow the same as revenue?
No. Revenue is the income generated from business activities under the applicable accounting rules. Cash flow reflects actual cash movements, which may occur before or after revenue is recognized.
14. How often should a business monitor cash flow?
Many small businesses review cash flow weekly or monthly, depending on their transaction volume and financial position. Businesses with tight cash reserves or unpredictable customer payments may benefit from more frequent reviews.