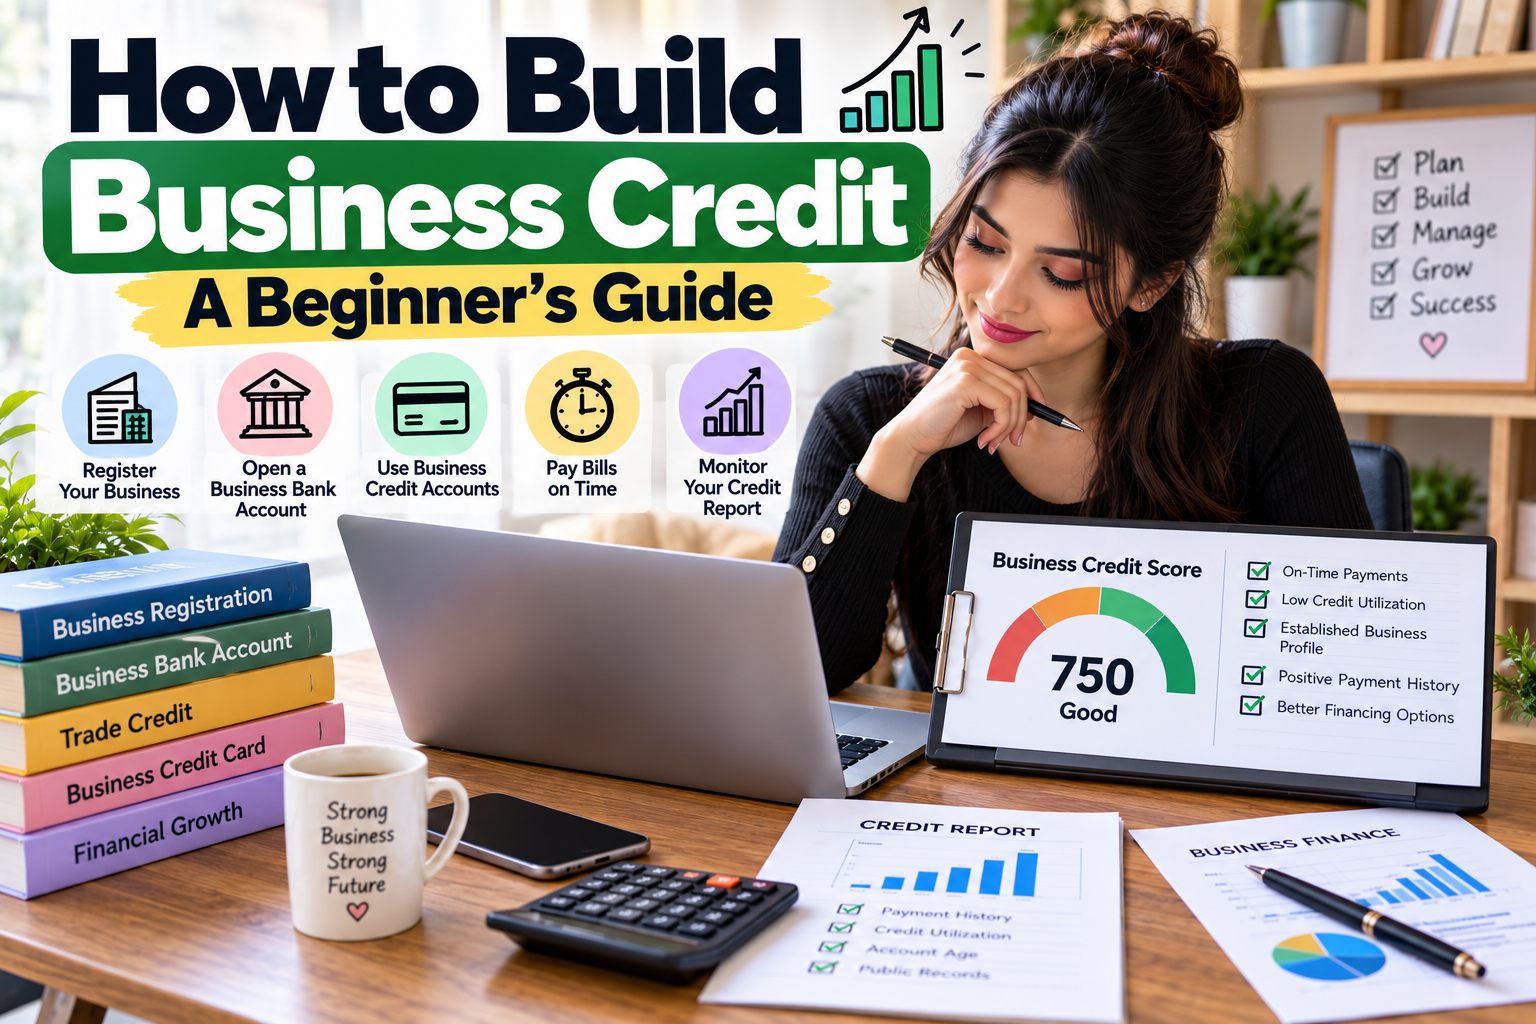
Building business credit is an important step for entrepreneurs who want to establish a financially credible company and prepare for future growth. A strong business credit profile may help a company qualify for certain financing products, negotiate supplier payment terms, and demonstrate financial reliability to potential business partners.
However, business credit does not develop automatically when you register a company or open a business bank account. It generally requires a combination of accurate business information, accounts that report payment activity, responsible borrowing, and consistent financial management.
For new business owners, the process can seem confusing. Different credit bureaus collect different information, lenders use their own approval criteria, and not every supplier or financial account reports payment history to business credit agencies.
The good news is that you can begin building a business credit profile through practical steps, even if your company is relatively new.
This guide explains how business credit works, how to establish a credit profile, which actions may help strengthen it, and which mistakes to avoid when managing business finances.
What Is Business Credit?
Business credit refers to a company's credit history and its perceived ability to meet financial obligations.
Depending on the country, industry, and credit reporting system, a business credit profile may include information about payment history, outstanding debts, public records, company details, and other financial indicators.
Lenders, suppliers, and certain business partners may use this information when deciding whether to extend credit or offer particular payment terms.
For example, a supplier might allow an established business to purchase inventory and pay the invoice within 30 days. A lender might review a company's credit profile alongside its revenue, cash flow, time in business, and other information when evaluating a loan application.
A business with a limited credit history may have fewer financing options or need to provide additional documentation.
It is important to understand that business credit is not a guarantee of financing. Each lender or supplier sets its own eligibility criteria.
Why Is Business Credit Important?
Business credit can support several aspects of company operations.
1. Access to Financing
Some lenders use business credit information when evaluating applications for loans, lines of credit, and business credit cards.
A stronger credit profile may improve eligibility for certain products, but approval also depends on factors such as business revenue, existing obligations, cash flow, and the owner's personal credit where applicable.
2. Supplier Payment Terms
Some suppliers offer trade credit, allowing eligible businesses to receive goods or services before paying the invoice.
For example, a supplier may provide net-30 terms, meaning payment is generally due 30 days after the invoice date, subject to the agreement.
A reliable payment history may help a business establish trust with suppliers and potentially qualify for suitable terms.
Not all suppliers report payment activity to business credit bureaus, so confirm their reporting practices before relying on a supplier account to build credit history.
3. Financial Credibility
A documented business credit history can provide additional information about a company's financial conduct.
Potential lenders, suppliers, and partners may consider it alongside other evidence when assessing financial reliability.
4. Separation of Business and Personal Finances
Maintaining separate business records and accounts makes it easier to understand company finances.
It can also help clarify which transactions belong to the business and which belong to the owner.
However, separating finances does not automatically eliminate personal liability. Some lenders may require a personal guarantee, particularly for new or small businesses.
Business Credit vs. Personal Credit
Business credit and personal credit are related concepts, but they serve different purposes.
Feature | Business Credit | Personal Credit |
|---|---|---|
Main subject | A company | An individual |
Typical uses | Business financing and supplier accounts | Personal loans, cards, and other consumer credit |
Information assessed | Business payment history and other company-related data | Personal borrowing and repayment history |
Reporting systems | Business credit bureaus, depending on the country | Consumer credit bureaus |
Approval considerations | Business history, revenue, obligations, and sometimes owner information | Personal income, credit history, debts, and other factors |
In the United States, business credit information may be maintained by organizations such as Dun & Bradstreet, Experian Business, and Equifax Business.
Their products, data sources, scoring methods, and coverage differ. A business may have information recorded by one bureau but limited or different information available from another.
In other countries, the relevant credit reporting systems and business financing rules may differ.
For new companies, lenders may still review the owner's personal credit or request a personal guarantee. Business credit and personal credit should therefore be managed as separate but potentially connected parts of financial planning.
Step 1: Establish a Legally Recognized Business
The first step is to establish your business in accordance with the rules that apply in your location.
Depending on your circumstances, this may involve registering a business name, forming a legal entity, obtaining tax identification, or securing required permits.
The appropriate structure depends on the business model, liability considerations, tax rules, and administrative costs.
For example, some businesses operate as sole proprietorships where permitted, while others form a limited liability company or corporation.
Creating a separate legal entity may help establish a distinct business identity, but it also introduces ongoing compliance requirements in many jurisdictions.
Before choosing a structure, understand the registration fees, annual filings, tax obligations, and recordkeeping responsibilities.
Step 2: Obtain the Required Business Identifiers
Credit reporting organizations and financial institutions may use business identifiers to match information to the correct company.
The identifiers required depend on the country, bureau, lender, and type of account.
In the United States, a company may use an Employer Identification Number (EIN) for federal tax purposes where applicable. Some organizations also use a Dun & Bradstreet D-U-N-S Number for business identification.
These identifiers serve different purposes and are not interchangeable.
A D-U-N-S Number is not a credit score, and obtaining an identifier does not automatically create a strong business credit profile.
Check the requirements of the institutions you intend to work with and ensure that the information associated with your business is accurate.
Step 3: Open a Dedicated Business Bank Account
A business bank account helps separate company transactions from personal spending.
This can improve recordkeeping and make it easier to track revenue, expenses, supplier payments, and loan repayments.
A dedicated account may also help lenders understand the business's financial activity when they request bank statements.
Financial institutions have different eligibility requirements, which may include registration documents, identification, tax information, and details about the company's owners.
If you operate internationally, verify that the bank or payment provider accepts businesses registered in your jurisdiction and supports your intended activities.
Opening a business bank account does not automatically build a business credit score, but it can help establish sound financial management practices.
Step 4: Keep Business Information Consistent
Inconsistent company information can make it harder for financial institutions and credit bureaus to match records correctly.
Use accurate, consistent details across relevant business documents and accounts.
These may include:
Registered business name.
Business address.
Telephone number and email.
Registration information.
Tax identification details.
Ownership and management records.
If your company changes its address or legal name, update the relevant records.
Review account statements and credit reports for incorrect details that could affect the business's financial profile.
Do not provide false information or use an address in a way that violates a provider's requirements.
Step 5: Establish Accounts That May Report Payment History
One way businesses may build credit history is by using eligible accounts that report payment activity to business credit bureaus.
Examples may include certain supplier trade accounts, business credit cards, and business loans.
However, reporting practices vary. Not every account reports to every bureau, and some providers report only certain types of information.
Before opening an account, ask:
Does the provider report to business credit bureaus?
Which bureau or bureaus receive the information?
Does the provider report on-time payments as well as late payments?
Are there fees, interest charges, or minimum purchase requirements?
Is a personal guarantee required?
Choose accounts that serve a genuine business need.
Avoid purchasing unnecessary products or paying excessive fees solely in the hope of building credit.
Understanding Supplier Trade Credit
Supplier trade credit allows a business to obtain goods or services and pay according to agreed terms.
For example, a supplier may approve an eligible company for net-30 terms.
If the account reports payment information to a relevant business credit bureau, consistent payments may contribute to the company's credit history.
However, supplier terms do not always appear on credit reports. Confirm the provider's reporting practices before relying on this approach.
Step 6: Pay Bills on Time
Payment history can be an important factor in business credit evaluations.
Paying invoices and credit obligations by their due dates helps demonstrate responsible financial management.
Set up reminders, use accounting software, or schedule payments where appropriate.
Maintain enough available cash to cover obligations before their deadlines.
If your business relies on customer invoices, monitor expected collection dates and prepare for possible delays.
Avoid assuming that a supplier's willingness to extend credit means that payment timing is unimportant.
Late payments can result in fees, strained supplier relationships, and potentially negative credit reporting, depending on the account and reporting system.
If you expect a payment problem, contact the creditor or supplier early to discuss available options rather than ignoring the obligation.
Step 7: Use Business Credit Responsibly
Access to credit can help a business manage short-term expenses or finance appropriate growth, but borrowing creates obligations.
If you have a business credit card, use it for legitimate company expenses that fit your budget.
Review interest rates, annual fees, repayment requirements, and any introductory offers carefully.
Paying the statement balance in full when feasible can help avoid interest on purchases under the card's terms, although payment rules vary by product.
If you use a revolving credit facility, monitor the outstanding balance and ensure that repayments remain manageable.
A high credit limit does not mean the business should borrow the full amount.
The goal is to use credit strategically, not to create debt simply to demonstrate activity.
Step 8: Monitor Business Credit Reports
Checking your business credit reports can help you understand what information lenders or suppliers may see.
Depending on the bureau, you may be able to review company details, payment records, public filings, and other reported information.
Consider reviewing reports from the business credit bureaus relevant to your market.
Check for:
Incorrect business information.
Accounts that do not belong to your company.
Payment records that appear inaccurate.
Duplicate or outdated information.
Incorrect outstanding balances.
Public records that may have been reported incorrectly.
If you find an error, follow the bureau's official dispute process and provide supporting documentation.
Keep copies of invoices, payment confirmations, statements, and correspondence.
Not every bureau provides the same report or score, so do not assume that a single score represents your complete business credit profile.
Step 9: Keep Debt at a Manageable Level
A business credit profile is only one part of financial health.
Taking on too much debt can create repayment pressure even if your credit history looks positive.
Before borrowing, estimate whether the business can afford repayments under different revenue scenarios.
Consider interest, fees, payment schedules, existing obligations, and the possibility that sales may fall below expectations.
For example, a loan used to purchase equipment may be reasonable if the equipment supports reliable revenue generation. The same loan could be risky if the business has not validated customer demand.
Use financing for a clear business purpose and evaluate its expected benefits against its costs.
Step 10: Build Relationships With Suppliers and Lenders
Reliable business relationships can support future financing and purchasing opportunities.
Communicate clearly, pay invoices according to agreed terms, and maintain accurate records.
When negotiating supplier credit, ask about eligibility, payment deadlines, credit limits, and reporting practices.
For lenders, prepare organized financial statements, bank records, tax documents, and a realistic business plan when requested.
A good relationship does not guarantee credit approval, but transparent communication and reliable payment practices can help demonstrate that your business manages its obligations responsibly.
How Long Does It Take to Build Business Credit?
There is no universal timeline for establishing business credit.
The time required depends on the business's age, the types of accounts it opens, reporting practices, payment activity, and the information collected by relevant bureaus.
A new business may initially have a limited credit file. Some accounts may begin appearing on a report after they are opened and reported, while other information may take longer to become available.
Building a meaningful credit history generally requires consistent activity over time.
Avoid companies that promise guaranteed credit scores or instant access to financing in exchange for large upfront fees.
Instead, focus on accurate records, appropriate accounts, timely payments, and regular credit report reviews.
Common Business Credit Mistakes to Avoid
1. Mixing Personal and Business Expenses
Using one account for everything can make financial records confusing.
Maintain clear records and use appropriate business accounts for company transactions.
2. Assuming Registration Automatically Builds Credit
Registering a company establishes a business identity, but it does not necessarily create a credit history.
Credit reporting generally depends on the information collected and reported by relevant providers.
3. Opening Too Many Accounts
Applying for several financial products without a clear need can create unnecessary costs and administrative work.
Some applications or accounts may affect how lenders evaluate the business, depending on the reporting system.
Choose accounts carefully and review their terms before applying.
4. Missing Payment Deadlines
Late payments may create fees and harm supplier relationships. Depending on the account and bureau, they may also affect the credit profile.
Use reminders and maintain sufficient cash to cover expected payments.
5. Ignoring Credit Reports
Incorrect information may remain on a report unless it is identified and addressed.
Review available reports periodically and dispute inaccuracies through official channels.
6. Borrowing More Than the Business Can Afford
Excessive borrowing can weaken cash flow and make it difficult to meet obligations.
Evaluate repayment capacity before accepting financing.
7. Paying for Unnecessary Credit-Building Services
Be cautious of providers that promise guaranteed results or claim that a particular score can be created immediately.
Research the provider, review the contract, and understand what the service actually offers before paying.
How to Build Business Credit for a New Company
A new company can begin by following a practical sequence.
First, establish the business legally and obtain the required identifiers.
Second, open a dedicated business bank account and maintain accurate company records.
Third, identify suppliers and financial institutions that serve your business and report relevant account information.
Fourth, use suitable accounts for genuine business needs and pay obligations on time.
Fifth, review available business credit reports and correct inaccurate information.
Finally, maintain manageable debt and consistent financial records as the business grows.
A new company may need to rely partly on the owner's personal credit or a personal guarantee when applying for financing. This depends on the lender and the company's financial history.
There is no guaranteed shortcut, but consistent financial management can help create a more credible business profile over time.
Conclusion
Building business credit is a gradual process that depends on accurate business information, appropriate financial accounts, responsible borrowing, and reliable payment practices.
Start by establishing your business identity, separating company finances, and understanding which accounts report payment information to relevant credit bureaus.
Pay bills on time, monitor your credit reports, and avoid unnecessary debt or services that promise guaranteed results.
Remember that business credit is only one part of financial health. Lenders and suppliers may also evaluate revenue, cash flow, profitability, time in business, and other factors.
By building a consistent financial record and managing obligations carefully, you can prepare your company for potential financing opportunities and support its long-term development.
Frequently Asked Questions (FAQs)
1. How do I build business credit for the first time?
Start by establishing your business legally, obtaining the required identifiers, opening a dedicated business bank account, and maintaining consistent company information. Then consider suitable accounts that report payment activity and pay obligations on time.
2. How long does it take to build business credit?
There is no fixed timeline. It depends on the business, account activity, reporting practices, and the information available to credit bureaus. A meaningful credit history generally develops through consistent financial activity over time.
3. Does registering a business automatically build credit?
No. Registration establishes a legal or business identity, depending on the structure and jurisdiction. It does not automatically create a strong credit history or guarantee that a credit score will be available.
4. Can I build business credit without using personal credit?
Sometimes. Certain business accounts may be available based on company information and financial performance. However, new or small businesses may be asked for a personal guarantee or personal credit review.
5. What is a business credit score?
A business credit score is a numerical assessment produced by a credit reporting organization or scoring system using available business-related information. Scoring methods and ranges vary by provider.
6. Which companies report business credit?
Reporting practices depend on the provider and account type. Some suppliers, lenders, and business card issuers report payment activity to particular business credit bureaus. Always confirm directly with the provider.
7. Does a business bank account help build business credit?
A business bank account can help separate finances and establish organized records, but opening one does not automatically create a business credit score. Its main benefit is supporting financial management and documentation.
8. Is business credit different from personal credit?
Yes. Business credit focuses on a company's credit-related information, while personal credit relates to an individual's borrowing history. However, lenders may review both when evaluating small-business financing applications.
9. Can a new LLC get a business credit card?
An LLC may qualify for a business credit card if it meets the issuer's requirements. Approval may depend on business information, revenue, time in business, and the owner's personal credit or guarantee.
10. How can I improve my business credit profile?
Maintain accurate business records, pay bills on time, use suitable credit accounts responsibly, keep debt manageable, and review credit reports for errors. Results depend on the reporting system and the company's overall financial circumstances.
11. What is trade credit?
Trade credit allows a business to obtain goods or services from a supplier and pay later under agreed terms. Some supplier accounts may report payment activity to business credit bureaus, but not all do.
12. Can I build business credit with no revenue?
A business with no revenue may be able to establish some business records or qualify for certain accounts, depending on the provider. However, limited revenue can restrict financing options, and approval is never guaranteed.
13. Should I pay a company to build business credit?
Not necessarily. Many foundational steps involve accurate registration, appropriate accounts, responsible payments, and regular report monitoring. Before paying a service, verify its fees, claims, and specific benefits.
14. Why should I check my business credit report?
Checking your report helps identify inaccurate information, unfamiliar accounts, and outdated records. Correcting errors through the official dispute process can help ensure that the profile reflects the available evidence accurately.