Deals are a fundamental part of the global business and financial system. Companies use deals to acquire competitors, enter new markets, raise capital, secure technology, form strategic partnerships, expand internationally, restructure operations, and create new sources of growth.
A business deal can be as simple as a supplier agreement or as complex as a multibillion-dollar merger between multinational corporations. Deals can involve cash, shares, debt, assets, intellectual property, partnerships, licenses, or combinations of different forms of consideration.
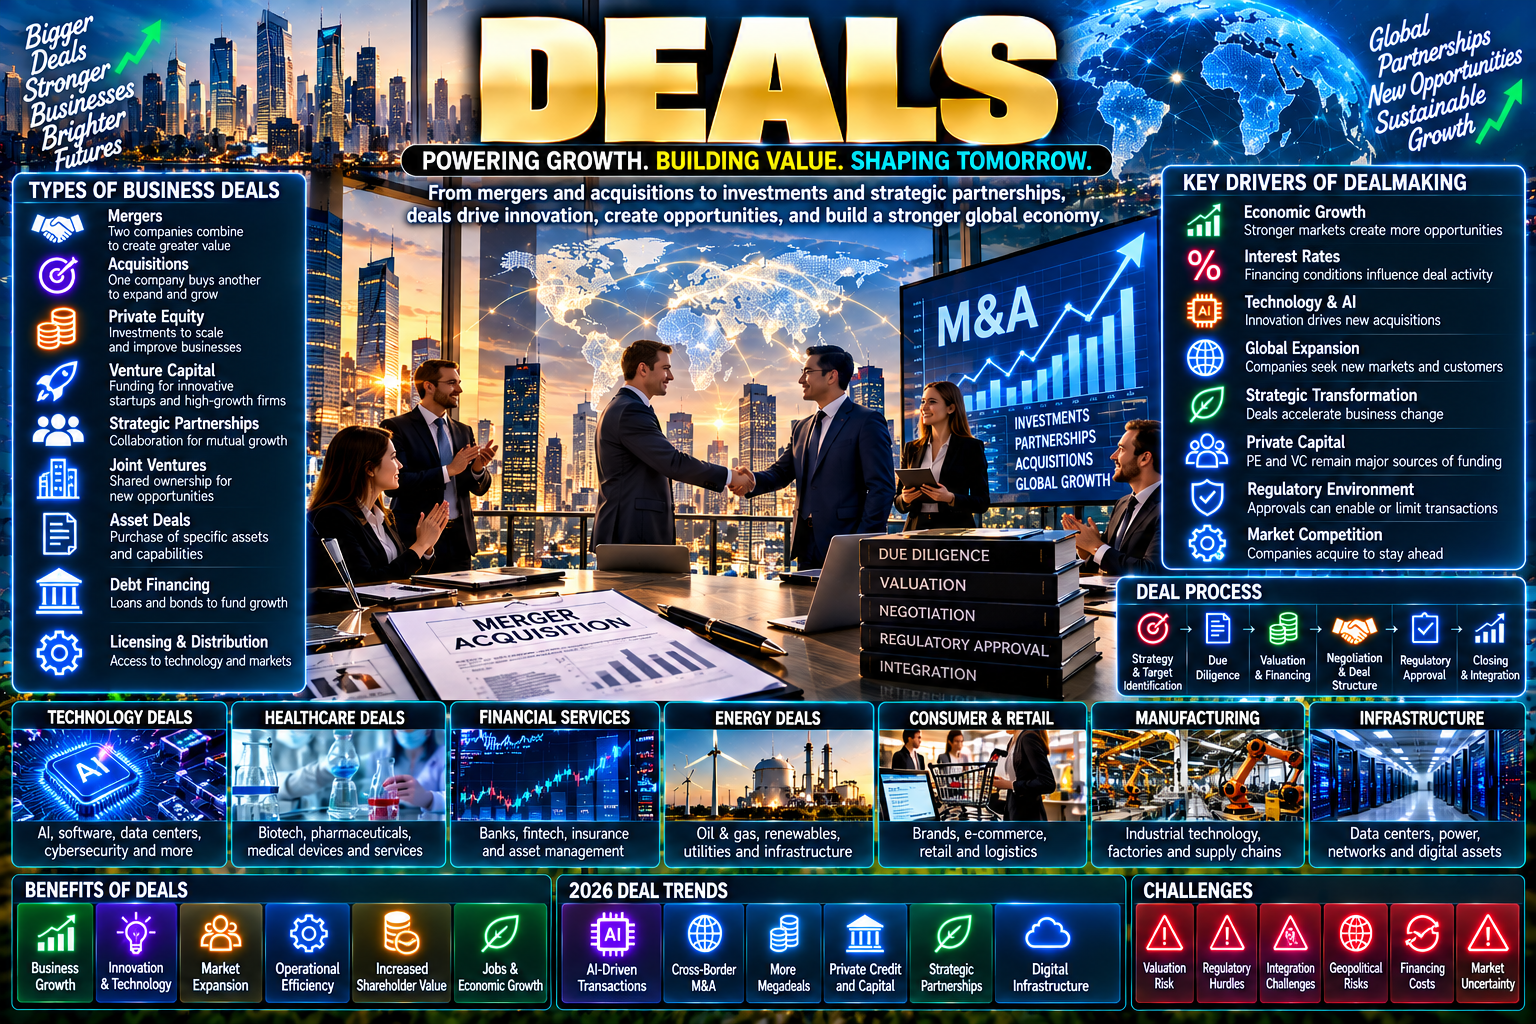
In financial markets, the term deal is often associated with mergers and acquisitions (M&A), private-equity investments, venture-capital funding, debt financing, initial public offerings, joint ventures, and strategic transactions.
The global dealmaking environment in 2026 is being shaped by artificial intelligence, interest rates, geopolitical uncertainty, financing conditions, technology investment, private capital, and changing corporate strategies.
PwC's 2026 mid-year M&A outlook projects global M&A value at approximately $4 trillion for 2026, while the number of deals is projected to be around 42,000. PwC notes that deals above $5 billion account for an increasingly large share of total deal value.
What Is a Business Deal?
A business deal is an agreement between two or more parties involving the exchange of money, assets, services, ownership, rights, or other forms of economic value.
Deals can involve:
Companies
Investors
Governments
Banks
Private-equity firms
Venture-capital firms
Entrepreneurs
Strategic partners
Suppliers
Customers
The objectives can vary significantly.
A company might make a deal to:
Increase revenue
Enter a new market
Acquire technology
Gain customers
Reduce costs
Expand production
Access talent
Raise capital
Strengthen its supply chain
Diversify its business
Major Types of Business Deals
Business deals come in many forms.
1. Mergers
A merger combines two businesses into a single corporate structure.
The companies may merge to achieve:
Greater scale
Cost efficiencies
Market expansion
Technology access
Product diversification
Increased market reach
The exact legal and financial structure depends on the transaction.
2. Acquisitions
An acquisition occurs when one company purchases another company or a controlling interest in it.
The buyer may acquire:
The entire company
A controlling stake
Specific business divisions
Selected assets
Intellectual property
Customer relationships
Acquisitions can be financed with cash, shares, debt, or combinations of these.
3. Private-Equity Deals
Private-equity firms invest capital into companies with the intention of generating returns through growth, operational improvements, restructuring, recapitalization, or eventual sale.
Private-equity deals can include:
Buyouts
Growth investments
Platform acquisitions
Add-on acquisitions
Recapitalizations
Continuation vehicles
PwC's 2026 outlook says private-equity dealmaking remains selective, with macroeconomic uncertainty, financing conditions and exit constraints affecting activity.
4. Venture-Capital Deals
Venture-capital deals provide funding to startups and high-growth companies.
Investors may receive equity in exchange for capital.
Funding rounds can include:
Pre-seed
Seed
Series A
Series B
Series C
Later-stage financing
Venture capital is particularly important in sectors such as:
Artificial intelligence
Software
Biotechnology
Fintech
Cybersecurity
Robotics
Climate technology
5. Strategic Partnerships
Not every deal involves buying another company.
A strategic partnership allows businesses to cooperate while remaining separate organizations.
Examples include agreements involving:
Technology
Distribution
Marketing
Manufacturing
Research
Licensing
Data
Cloud services
Strategic partnerships can provide access to capabilities without the full cost and complexity of an acquisition.
6. Joint Ventures
A joint venture occurs when two or more parties establish or operate a business together.
Each participant may contribute:
Capital
Technology
Employees
Intellectual property
Distribution networks
Manufacturing capacity
Market access
Joint ventures are particularly useful when entering markets where local knowledge or infrastructure is important.
7. Asset Deals
A company does not always need to buy another entire company.
An asset deal involves purchasing selected assets.
These can include:
Factories
Equipment
Brands
Patents
Software
Customer contracts
Real estate
Product lines
Asset transactions can allow buyers to obtain specific capabilities without acquiring the entire corporate entity.
8. Debt Financing Deals
Businesses can also raise capital by borrowing money.
Debt deals include:
Corporate bonds
Bank loans
Private credit
Convertible debt
Structured financing
The borrower generally has an obligation to repay the capital according to agreed terms.
In 2026, private credit and nonbank lenders remain important sources of deal financing. Deloitte's research highlights the continued role of private credit alongside cash and equity financing.
9. Licensing Deals
A licensing agreement allows one party to use another party's intellectual property under specified conditions.
Licensed assets can include:
Patents
Software
Trademarks
Media rights
Technology
Pharmaceutical compounds
Content
The licensee may pay an upfront fee, royalties, or both.
10. Distribution Deals
Distribution agreements allow companies to sell products through another company's network.
A manufacturer might partner with:
Retailers
Wholesalers
E-commerce platforms
Logistics companies
Regional distributors
These deals can help companies expand without building their own distribution infrastructure.
How a Deal Works
A major corporate deal generally follows several stages.
1. Strategy
The buyer identifies what it wants to accomplish.
2. Target Identification
Potential companies, assets or partners are identified.
3. Initial Discussions
The parties discuss strategic objectives, valuation and transaction structure.
4. Letter of Intent
A preliminary agreement may outline key commercial terms.
5. Due Diligence
The buyer examines the target in detail.
6. Valuation
The parties determine an appropriate transaction value.
7. Financing
The buyer arranges cash, debt, equity or other financing.
8. Negotiation
The parties negotiate definitive terms.
9. Legal Documentation
Lawyers prepare and review the final agreements.
10. Regulatory Review
Some transactions require approval from regulators.
11. Closing
The transaction is legally completed.
12. Integration
For acquisitions and mergers, the businesses may then be integrated.
What Is Due Diligence?
Due diligence is the process of investigating a company or transaction before completing a deal.
It can cover:
Financial statements
Revenue
Profitability
Debt
Cash flow
Tax
Legal issues
Employees
Customers
Suppliers
Intellectual property
Cybersecurity
Technology
Regulatory compliance
Environmental issues
Litigation
The objective is to understand what the buyer is actually purchasing and identify risks that could affect the transaction.
Financial Due Diligence
Financial analysis examines the target's economic performance.
Important areas include:
Revenue growth
Gross margins
EBITDA
Operating expenses
Free cash flow
Working capital
Debt
Capital expenditure
Customer concentration
Recurring revenue
Buyers often investigate whether reported financial performance is sustainable.
Legal Due Diligence
Legal teams may examine:
Corporate ownership
Contracts
Litigation
Intellectual property
Employment agreements
Licenses
Regulatory compliance
Data protection
Real-estate agreements
Unresolved legal issues can affect both valuation and deal structure.
Technology Due Diligence
Technology has become increasingly important in modern deals.
Technology diligence can examine:
Software architecture
Cloud infrastructure
Cybersecurity
Data
AI systems
Intellectual property
Technical debt
Engineering teams
Scalability
This is especially important for technology companies.
AI is also changing how buyers assess potential targets.
PwC reports that AI is increasingly being incorporated into deal sourcing, diligence, valuation and investment-committee preparation.
How Companies Value Deals
Valuation is one of the most important parts of a transaction.
Common valuation approaches include:
Comparable Companies
The target is compared with similar publicly traded companies.
Precedent Transactions
The buyer examines prices paid in similar transactions.
Discounted Cash Flow
Future cash flows are estimated and discounted to their present value.
EBITDA Multiples
A transaction value may be compared with earnings before interest, taxes, depreciation and amortization.
Revenue Multiples
Revenue multiples are frequently used for certain high-growth technology businesses.
No single valuation method is appropriate for every company.
Deal Structure
A transaction can be structured in different ways.
Cash Deal
The buyer pays cash.
Stock Deal
The seller receives shares in the acquiring company.
Cash-and-Stock Deal
The transaction combines cash and equity.
Earnout
Part of the purchase price depends on future performance.
Debt-Financed Deal
The buyer uses borrowing to fund part of the acquisition.
Seller Financing
The seller provides financing to the buyer.
The structure can influence risk, taxes, control, liquidity and future incentives.
Deal Financing
Financing is critical to large transactions.
Common sources include:
Cash on balance sheet
Bank loans
Corporate bonds
Private credit
Equity issuance
Private-equity capital
Venture capital
Seller financing
Strategic investors
Financing costs can materially affect the economics of a transaction.
Higher interest rates can make debt-financed acquisitions more expensive.
Private Credit and Deals
Private credit has become increasingly important in transaction financing.
Private-credit providers can offer customized financing to companies that may not rely entirely on traditional bank lending.
Deloitte's 2026 M&A research highlights private credit and nonbank lenders as important deal-financing mechanisms, alongside cash and equity.
Private credit can provide flexibility, but borrowers and investors must evaluate interest costs, covenants, repayment requirements and credit risk.
M&A in 2026
M&A activity in 2026 is being shaped by a combination of technology investment, capital availability, macroeconomic uncertainty and changing corporate strategies.
PwC's mid-year 2026 outlook projects approximately $4 trillion in global M&A value, about 13% above 2025, while projecting roughly 42,000 transactions, about 13% fewer than 2025.
This difference illustrates an important feature of the market: a smaller number of very large transactions can account for a substantial share of total deal value.
PwC says transactions above $5 billion represented approximately 48% of global M&A value in its 2026 mid-year analysis.
AI and Business Deals
Artificial intelligence has become one of the major forces influencing dealmaking.
AI affects deals in two different ways.
AI as a Deal Target
Investors may seek companies developing:
AI models
AI applications
AI infrastructure
Data platforms
AI chips
Cybersecurity
Automation technology
AI as a Deal Driver
Companies may acquire businesses because AI can transform:
Revenue
Productivity
Customer service
Software development
Data analysis
Operations
Supply chains
PwC's 2026 analysis says AI is influencing major transactions and reshaping deal strategy across industries.
AI Infrastructure Deals
AI investment extends beyond software.
Large amounts of capital are flowing toward:
Data centers
Power generation
Electricity grids
Semiconductors
Networking
Cooling systems
Digital infrastructure
PwC identifies AI-related investment in data centers, energy and other infrastructure as an important theme in the 2026 deal environment.
This means companies in traditional infrastructure industries can become part of the AI deal ecosystem.
Cross-Border Deals
Cross-border deals involve companies located in different countries.
These transactions can provide access to:
New customers
New technology
Lower-cost production
International talent
New supply chains
Regional distribution
Local market knowledge
But they also create additional complexity.
Cross-border transactions may require analysis of:
Foreign-exchange risk
Tax
Local regulations
Political conditions
Trade rules
Employment law
Cultural differences
Data regulations
Supply-chain requirements
Deloitte's June 2026 survey found that 65% of surveyed dealmakers expected cross-border M&A activity to increase over the following 12 months, while emphasizing execution risks involving compliance, supply chains, tax and revenue synergies.
Deals by Industry
Deal activity varies significantly by sector.
Technology
Technology deals can involve:
Software
AI
Cloud computing
Cybersecurity
Data infrastructure
Semiconductors
Healthcare
Healthcare deals can involve:
Biotechnology
Pharmaceuticals
Medical devices
Healthcare services
Digital health
Financial Services
Financial deals include:
Banks
Insurance companies
Asset managers
Fintech
Wealth management
Energy
Energy deals can include:
Oil and gas
Renewable energy
Utilities
Power infrastructure
Energy storage
Manufacturing
Manufacturing deals can involve:
Factories
Industrial technology
Automation
Machinery
Supply chains
Consumer and Retail
Companies may acquire:
Consumer brands
E-commerce businesses
Retail networks
Logistics companies
Digital platforms
Deal Synergies
A major reason companies pursue acquisitions is the possibility of synergies.
Synergies generally fall into two categories.
Revenue Synergies
The combined company may generate additional revenue through:
Cross-selling
New customers
New products
Geographic expansion
Distribution
Pricing opportunities
Cost Synergies
The combined business may reduce costs through:
Shared infrastructure
Consolidated offices
Procurement
Technology
Administration
Supply-chain efficiencies
However, projected synergies do not automatically become real results.
They must be implemented successfully after closing.
Integration After a Deal
Closing a deal is not the end of the process.
Integration can involve:
Combining technology systems
Aligning employees
Restructuring departments
Integrating financial systems
Combining customer databases
Consolidating suppliers
Updating branding
Aligning corporate cultures
Poor integration can reduce the expected benefits of an acquisition.
Deal Risks
Business deals involve significant risks.
Valuation Risk
The buyer may pay too much.
Financing Risk
Interest rates or financing conditions may change.
Integration Risk
The businesses may be difficult to combine.
Regulatory Risk
Authorities may delay, modify or block a transaction.
Technology Risk
A target's technology may be less valuable or scalable than expected.
Customer Risk
Customers may leave after an acquisition.
Employee Risk
Key employees may depart.
Market Risk
Economic conditions may change between signing and closing.
Geopolitical Risk
International transactions can be affected by trade restrictions and political developments.
Regulatory Review
Large deals may require review by competition or other regulatory authorities.
Regulators can examine whether a transaction could:
Reduce competition
Increase market concentration
Harm consumers
Restrict access to essential services
Create national-security concerns
The requirements depend on the countries and industries involved.
Cross-border transactions can therefore require regulatory analysis in multiple jurisdictions.
Deal Negotiation
Negotiation determines many of the economic and legal terms of a transaction.
Important negotiation points can include:
Purchase price
Payment structure
Closing conditions
Representations and warranties
Indemnification
Earnouts
Management retention
Employee arrangements
Non-compete provisions
Financing conditions
Regulatory requirements
Strong negotiation requires understanding both financial and operational factors.
Deal Documentation
Large deals can involve extensive legal documentation.
Common documents may include:
Confidentiality agreements
Letters of intent
Term sheets
Purchase agreements
Shareholder agreements
Financing agreements
Employment agreements
Transition-service agreements
Regulatory filings
Lawyers, financial advisers, tax specialists and other professionals often work together throughout the transaction.
Investment Banks and Deal Advisers
Investment banks and advisory firms often assist with major transactions.
Their services can include:
Valuation
Deal sourcing
Buyer identification
Seller preparation
Negotiation support
Financing
Market analysis
Due diligence coordination
The global advisory market includes investment banks, accounting firms, law firms, private-equity advisers and specialist consultants.
Recent market activity also shows continued competition among major investment banks for M&A mandates. Reuters reported in September 2026 that Goldman Sachs had ranked first in UK M&A by announced transaction value for 2026 at that point, with $175 billion across 69 deals.
Deals and Private Equity Exits
Private-equity firms generally seek ways to eventually realize their investments.
Common exit routes include:
Sale to another company
Sale to another private-equity firm
Initial public offering
Secondary transaction
Recapitalization
Management buyout
The exit environment can influence new deal activity because private-equity firms need liquidity to return capital to investors and recycle capital into new investments.
PwC reported in its 2026 mid-year private-equity outlook that exit constraints and ageing portfolio companies remained important factors affecting deal activity.
Deals and Startups
For startups, financing deals can determine how quickly a company can grow.
A startup may raise capital in exchange for equity.
Investors may evaluate:
Market size
Revenue growth
Technology
Competitive position
Founding team
Customer acquisition
Unit economics
Intellectual property
Future financing requirements
As startups mature, deals can progress from venture financing to strategic investment, acquisition or public-market transactions.
Deals and Digital Transformation
Digital transformation is another major deal driver.
Companies may acquire technology businesses to obtain:
Cloud capabilities
AI
Data analytics
Automation
Cybersecurity
Software
Digital customer platforms
Deloitte's research identifies digital transformation and AI as continuing areas of focus within the M&A lifecycle.
AI is also increasingly used by deal teams themselves for research, diligence, document review, data analysis and preparation.
How AI Is Changing Deal-Making
AI can potentially improve several stages of the transaction process.
Deal Sourcing
AI can identify potential acquisition targets based on financial and strategic criteria.
Due Diligence
AI can analyze large volumes of contracts and documents.
Market Research
AI can process industry and competitor information.
Valuation
AI tools can assist with financial modeling and scenario analysis.
Integration
AI can help identify overlapping processes, customers and systems.
However, AI-generated analysis requires human review.
Important decisions involving valuation, legal obligations, financial assumptions and risk should not rely solely on automated outputs.
Global Deal Trends in 2026
Several themes are defining the current deal environment.
Megadeals
Large transactions are accounting for an increasingly significant share of global M&A value.
AI
AI is influencing both what companies buy and how transactions are executed.
Infrastructure
Data centers, power and digital infrastructure are attracting deal attention as AI investment expands.
Private Credit
Nonbank financing continues to play an important role in deal funding.
Cross-Border Transactions
International acquisitions remain an important growth strategy, although regulatory and execution risks remain significant.
Selectivity
PwC's mid-year analysis describes a more selective private-capital market, with financing, exit conditions and macroeconomic uncertainty affecting transaction activity.
How to Evaluate a Business Deal
A structured approach can help assess a potential transaction.
Strategic Fit
Does the deal support the company's long-term strategy?
Financial Value
Does the expected value justify the purchase price?
Market Position
Will the transaction improve the company's competitive position?
Synergies
Are projected cost or revenue synergies realistic?
Financing
Can the transaction be financed without creating excessive financial pressure?
Risks
What could cause the deal to underperform?
Integration
Can the businesses realistically be combined?
Regulation
Are there competition, tax, political or regulatory issues?
Exit
If the buyer is an investor, what are the potential future exit routes?
Deals vs. Investments
Deals and investments overlap but are not identical.
Feature | Business Deal | Investment |
|---|---|---|
Purpose | Can involve acquisition, partnership or financing | Primarily capital allocation |
Ownership | May or may not change | Often involves an ownership or financial claim |
Participants | Companies, investors, partners | Investors and asset issuers |
Structure | Highly variable | Shares, bonds, funds, loans, etc. |
Objective | Strategic or financial | Usually financial return |
Example | Company acquisition | Buying company shares |
A single transaction can be both a business deal and an investment.
The Future of Deals
The future of dealmaking is likely to be shaped by technology, capital availability and changing business models.
AI-Driven Due Diligence
Large volumes of documents and data can increasingly be processed using AI tools.
Digital Infrastructure
Data centers, cloud infrastructure and power systems may remain important areas of capital investment.
Cross-Border Expansion
Companies may continue pursuing international deals to diversify markets and supply chains.
Private Capital
Private equity, private credit and other private-market investors will remain important sources of transaction capital.
Specialized Acquisitions
Companies may increasingly acquire specific capabilities rather than entire businesses.
Data and Intellectual Property
Data, software, AI models and intellectual property can become increasingly important components of transaction value.
The Outlook for Business Deals
The 2026 deal market is active but uneven.
PwC's global M&A outlook projects approximately $4 trillion of global M&A value for 2026, with fewer transactions but a greater concentration of value in very large deals.
Private capital is also becoming more selective. PwC's mid-year analysis reports that private-equity deal volume in Q1 2026 was broadly flat year over year, while deal value declined 14%, reflecting a more cautious deployment environment.
At the same time, AI is influencing both investment targets and transaction processes, while infrastructure associated with AI—including data centers and energy—is creating new opportunities for capital deployment.
Cross-border dealmaking is another important theme. Deloitte's 2026 survey found substantial interest in international transactions, while emphasizing the need to manage compliance, tax, supply-chain and revenue-synergy risks.
These trends suggest that modern dealmaking is increasingly connected to technology, infrastructure, capital efficiency and strategic transformation.
Conclusion
Deals are one of the main mechanisms through which businesses grow, reorganize and compete.
Mergers and acquisitions can provide scale and new capabilities. Venture capital can finance emerging companies. Private equity can provide growth and acquisition capital. Strategic partnerships can open new markets without requiring full ownership. Debt and private credit can finance expansion and acquisitions.
In 2026, artificial intelligence is becoming a major force across the deal ecosystem. It is influencing acquisition targets, valuation, due diligence, financing, infrastructure investment and post-deal value creation.
At the same time, dealmakers must navigate interest rates, geopolitical uncertainty, regulation, financing costs, valuation differences and integration challenges.
A successful deal is therefore about more than agreeing on a price. It requires strategic planning, accurate valuation, rigorous due diligence, appropriate financing, effective negotiation, regulatory compliance and disciplined execution after closing.
As technology and capital markets continue to evolve, deals will remain a central mechanism for creating partnerships, transferring ownership, deploying capital and reshaping the global business landscape.
Frequently Asked Questions
What is a business deal?
A business deal is an agreement between parties involving the exchange of money, assets, ownership, services, rights or other economic value.
What is M&A?
M&A stands for mergers and acquisitions. It describes transactions in which companies combine, one company acquires another, or ownership interests change.
What is due diligence?
Due diligence is the detailed investigation of a company, asset or transaction before the deal is completed.
How are acquisitions financed?
Acquisitions can be financed using cash, debt, equity, private credit, seller financing or combinations of these sources.
What is a strategic partnership?
A strategic partnership is an agreement between businesses to cooperate in areas such as technology, distribution, marketing, manufacturing or research without necessarily combining ownership.
What is a private-equity deal?
A private-equity deal involves a private-equity investor providing capital to or acquiring an interest in a company.
How does AI affect business deals?
AI can influence which companies are acquired and can also assist with sourcing, due diligence, valuation, research, document analysis and post-deal integration.
What are the biggest risks in a business deal?
Major risks include overvaluation, financing problems, regulatory restrictions, integration difficulties, technology issues, customer losses, employee departures and changing economic conditions.
Are cross-border deals more complicated?
They can be because they may involve multiple legal systems, currencies, tax regimes, regulatory authorities, political environments and supply chains.
What is the 2026 dealmaking outlook?
Current 2026 research points to significant deal value but uneven activity, with large transactions, AI, infrastructure, private capital and cross-border opportunities playing important roles.