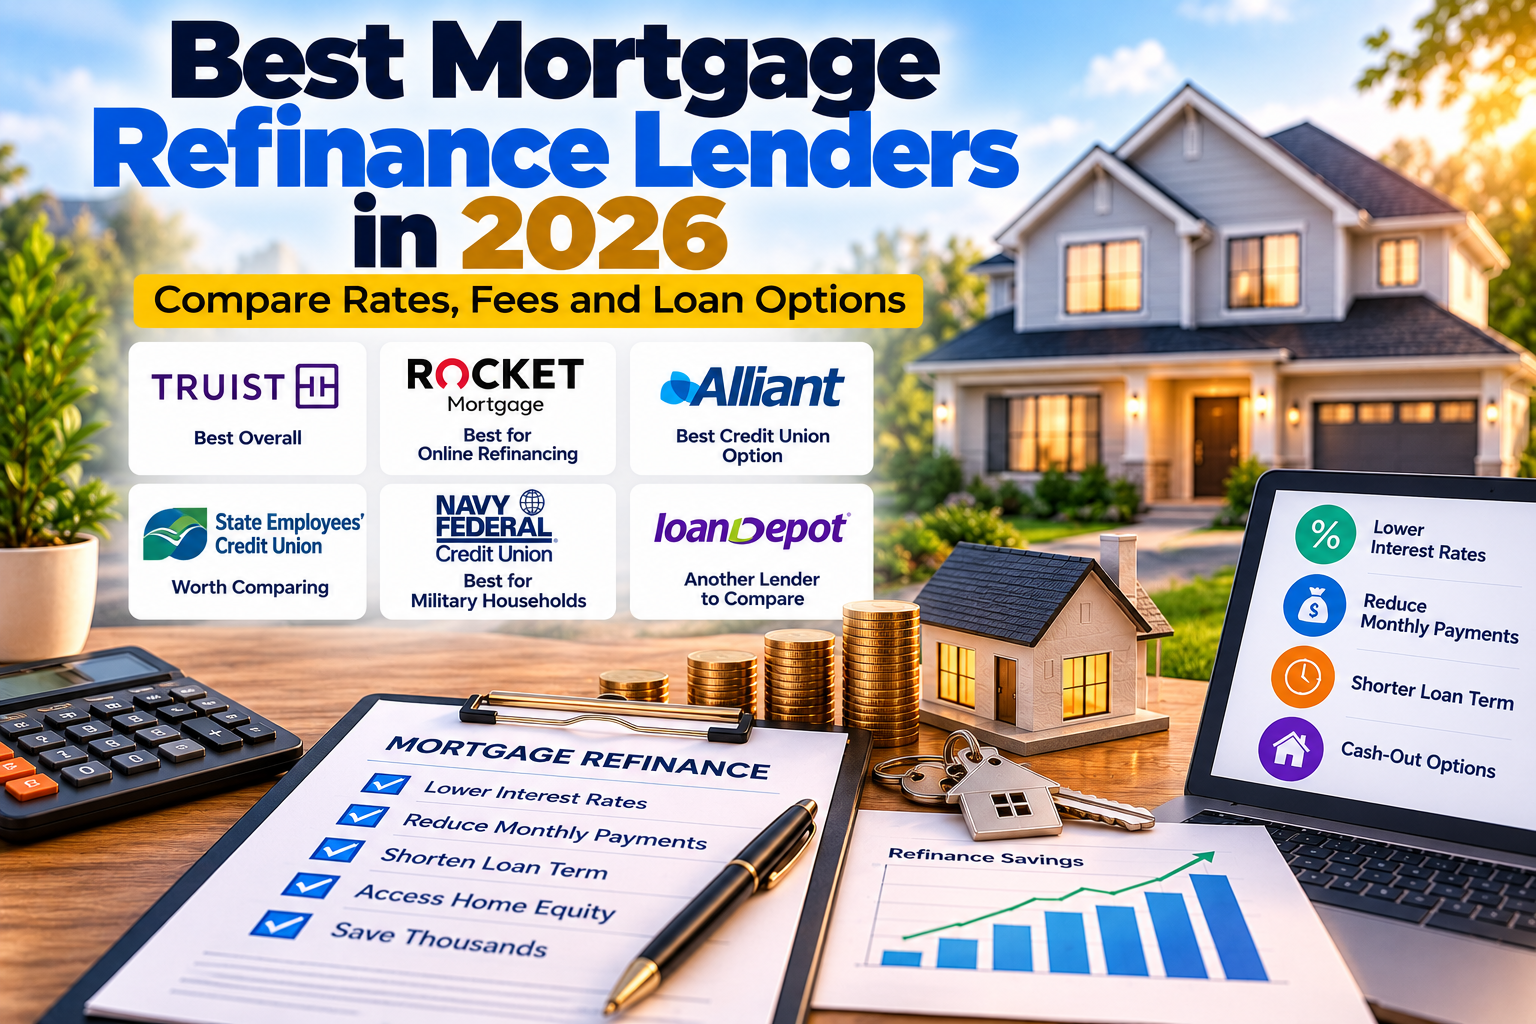
Refinancing a mortgage can help homeowners change their loan terms, reduce monthly payments, shorten their repayment period, or access home equity. However, choosing the right mortgage refinance lender requires more than finding the lowest advertised interest rate. Closing costs, credit requirements, loan programs, and the length of time you plan to stay in your home can all affect whether refinancing makes financial sense.
In 2026, homeowners can compare traditional banks, credit unions, and online mortgage lenders to find refinancing options that match their financial goals. Some lenders may be better suited to conventional refinancing, while others offer specialized programs for eligible veterans or homeowners who want to access their equity.
This guide explores the best mortgage refinance lenders to consider, explains how refinancing works, and provides practical steps for comparing loan offers.
What Is Mortgage Refinancing?
Mortgage refinancing means replacing your existing home loan with a new mortgage. The new loan pays off the remaining balance of your current mortgage, and you begin making payments according to the new loan's terms.
Homeowners generally refinance for four main reasons:
Lowering the interest rate: A lower rate may reduce borrowing costs if the savings outweigh refinancing expenses.
Changing the loan term: Moving from a 30-year mortgage to a 15-year mortgage may help you pay off your home faster.
Reducing monthly payments: A longer repayment term may lower monthly payments, although it can increase the total interest paid.
Accessing home equity: A cash-out refinance allows eligible homeowners to borrow more than they owe and receive the difference in cash.
Refinancing is not automatically beneficial. Homeowners should compare their current mortgage with the proposed loan, including fees and the total interest expected over the time they plan to keep the property.
Best Mortgage Refinance Lenders in 2026
The following lenders are worth researching when comparing mortgage refinancing options. Their suitability depends on your circumstances, and the list is not a guarantee of the lowest available rate.
1. Truist — Best Overall Option to Compare
Truist is a major financial institution offering mortgage products and refinancing options. NerdWallet selected Truist as its top overall mortgage lender for refinancing in its 2026 rankings, citing its competitive borrowing costs and range of options.
Why consider Truist?
Mortgage refinancing products for eligible borrowers.
A combination of online information and personal assistance.
Multiple mortgage options depending on eligibility.
An established banking network.
Potential drawback: The application and service experience may involve phone or in-person communication. Borrowers should confirm the availability of their preferred refinancing product in their state.
Best for: Homeowners who want to compare a traditional bank's refinancing offer with online lenders and credit unions.
2. Rocket Mortgage — Best for Online Refinancing
Rocket Mortgage is a major online mortgage lender that offers a digital application experience and several refinancing options. Its refinancing products may include conventional, FHA, VA, and jumbo loans, subject to eligibility.
Why consider Rocket Mortgage?
Online application and document submission.
Digital tools for tracking the mortgage process.
Options for rate-and-term and cash-out refinancing.
Specialized refinancing products for eligible FHA and VA borrowers.
Potential drawback: Online convenience does not necessarily mean the lowest total cost. Compare the lender's interest rate, APR, origination charges, and closing costs with competing offers.
Best for: Homeowners who prefer a digital mortgage application and want to compare several refinancing structures.
3. Alliant Credit Union — Best Credit Union to Investigate
Credit unions can be worth considering because their loan offerings and pricing may differ from those of large commercial banks. Alliant Credit Union appeared among the highest-rated refinance lenders in NerdWallet's 2026 analysis.
Why consider Alliant?
An alternative to large-bank mortgage financing.
Mortgage options that may suit eligible members.
An opportunity to compare rates and fees with other lenders.
Potential drawback: Membership rules, property eligibility, and available loan programs may affect whether you can apply.
Best for: Borrowers who want to compare a credit union's mortgage terms against those offered by banks and online lenders.
4. State Employees’ Credit Union — Worth Comparing for Eligible Borrowers
State Employees’ Credit Union (SECU) also received high marks in NerdWallet's 2026 refinance lender analysis. Its suitability depends on its membership rules and the specific mortgage products available to an applicant.
Why consider SECU?
A credit-union alternative to national mortgage lenders.
An additional quote to include when comparing refinance offers.
Potentially useful for borrowers who meet membership requirements.
Potential drawback: Eligibility and product availability can be limited by membership and geographic requirements. Verify these details before starting an application.
Best for: Eligible borrowers who want to compare credit-union financing with conventional mortgage lenders.
5. Navy Federal Credit Union — Best to Explore for Eligible Military Households
Navy Federal Credit Union serves eligible members of the military community, veterans, and qualifying family members. Homeowners with an existing VA mortgage may want to investigate its refinancing options.
Why consider Navy Federal?
Mortgage services for eligible military households.
Options to investigate for VA-related refinancing.
A credit-union alternative for borrowers who qualify for membership.
Potential drawback: Membership is restricted, and not every refinancing product is available to every applicant. Ask whether the lender offers a suitable option for your current mortgage.
Best for: Eligible military members, veterans, and family members who want to compare specialized mortgage refinancing options.
6. loanDepot — Another Lender to Compare
loanDepot is a mortgage lender that homeowners may include in their refinancing research. Its current product availability, underwriting requirements, and pricing should be checked directly before applying.
Why consider loanDepot?
An additional lender for obtaining a competing quote.
Mortgage expertise and refinancing options, depending on the current product lineup.
An opportunity to compare fees and service with other lenders.
Potential drawback: The interest rate and closing costs offered to one borrower may differ significantly from another borrower's quote.
Best for: Homeowners who want a broader comparison rather than relying on one bank or online lender.
Mortgage Refinance Lender Comparison
Lender | Main reason to compare | Important consideration |
|---|---|---|
Truist | Overall refinancing option | Compare current rates and fees |
Rocket Mortgage | Online application experience | Review total loan costs |
Alliant Credit Union | Credit-union alternative | Check membership eligibility |
State Employees’ Credit Union | Credit-union alternative | Confirm geographic and membership rules |
Navy Federal Credit Union | Military-related mortgage options | Membership restrictions apply |
loanDepot | Additional mortgage quote | Verify current products and fees |
These are starting points for research, not a definitive ranking for every borrower. Ask each lender for a personalized Loan Estimate before making a decision.
How to Choose the Best Mortgage Refinance Lender
1. Compare Interest Rates and APR
The interest rate determines the cost of borrowing principal, while the annual percentage rate (APR) includes the interest rate and certain loan costs. APR can help borrowers compare offers, although differences in loan structure and fees can make direct comparisons more complicated.
Request quotes from several lenders using the same loan amount, term, property details, and approximate closing date. A lender advertising a low rate may require discount points or charge fees that reduce the overall benefit.
2. Review Closing Costs
Mortgage refinancing often involves costs such as lender fees, appraisal charges, title services, recording fees, and prepaid expenses. The amount varies by lender, loan type, location, and property.
For illustration, refinancing a $300,000 mortgage with closing costs equal to 3% would mean $9,000 in costs. This is an example, not a quote or a universal fee estimate.
Ask for a written breakdown of charges and find out whether any fees are paid upfront, added to the loan, or offset by a higher interest rate.
3. Check Your Credit Profile
Your credit history can affect the interest rate and loan terms you qualify for. Before applying, review your credit reports for errors, make payments on time, and avoid unnecessary new debt where practical.
Lenders may also examine your income, existing debt payments, home equity, property value, and payment history. Requirements differ by loan program and lender.
4. Choose the Right Loan Term
A shorter mortgage term usually comes with higher monthly principal-and-interest payments but may reduce total interest over the life of the loan. A longer term can make payments more manageable but may extend the repayment period.
Compare both the monthly payment and total expected interest rather than choosing a loan based only on affordability today.
5. Understand Rate Locks and Loan Estimates
Ask how long a quoted interest rate can be locked and whether fees apply to the lock. Rates and loan terms can change before closing unless they are secured under the lender's rate-lock agreement.
Once you receive a Loan Estimate, compare it with the estimates from other lenders. Review the loan amount, interest rate, APR, estimated closing costs, monthly payment, and cash required at closing.
When Does Mortgage Refinancing Make Sense?
Refinancing may be worth investigating when:
Your current interest rate is higher than the rate you can qualify for now.
You expect to remain in the home long enough to recover the refinancing costs.
You want to switch from an adjustable-rate mortgage to a fixed-rate loan.
You want to shorten your repayment term and can comfortably afford the new payment.
You have a specific reason to access home equity and understand the additional borrowing risk.
Market interest rates alone do not determine whether refinancing is beneficial. Your existing mortgage terms and personal financial situation are equally important.
Calculate Your Break-Even Point
The break-even point estimates how long it takes for monthly savings to cover refinancing costs.
Formula:
Break-even period = Total refinancing costs ÷ Monthly savings
For example, suppose refinancing costs $6,000 and reduces your monthly payment by $200.
$6,000 ÷ $200 = 30 months.
You would need approximately 30 months to recover those costs through the monthly payment savings, assuming the savings remain consistent. If you sell the home or refinance again before then, you may not recover the costs.
This calculation is only a starting point. It does not account for differences in loan terms, changes in principal repayment, taxes, or all other financial effects.
Types of Mortgage Refinancing
Rate-and-Term Refinance
This replaces your current mortgage with a new loan that changes the interest rate, repayment term, or both. It is often considered by borrowers who want to improve their loan terms without receiving cash from their home equity.
Cash-Out Refinance
A cash-out refinance replaces the existing mortgage with a larger loan, subject to the property's value and lender requirements. The borrower receives the difference after the existing mortgage and applicable costs are paid.
This can provide funds for major expenses, but it increases or restructures debt secured by your home. Using home equity to repay unsecured debt can put the property at greater risk if you cannot make the new payments.
FHA Streamline Refinance
Eligible homeowners with existing FHA-insured mortgages may be able to use an FHA streamline refinance. The program has specific requirements and is not available to every borrower.
VA Interest Rate Reduction Refinance Loan
Eligible borrowers with VA-backed mortgages may qualify for a VA Interest Rate Reduction Refinance Loan, often called an IRRRL. Eligibility and program requirements apply, and borrowers should compare the costs against the expected benefits.
Fixed-Rate Refinance
A fixed-rate mortgage keeps the interest rate unchanged for the loan term. This can make principal-and-interest payments more predictable.
Adjustable-Rate Mortgage Refinance
An adjustable-rate mortgage may offer an initial fixed-rate period followed by rate adjustments. Borrowers should understand how frequently the rate can change, the applicable caps, and the maximum potential payment.
Common Mortgage Refinancing Mistakes to Avoid
Choosing a lender based only on its advertised rate. The APR, fees, points, and loan terms all affect the actual cost.
Ignoring the break-even point. A lower monthly payment may not compensate for closing costs if you plan to move soon.
Extending the loan without considering total interest. A new 30-year mortgage may reduce payments while increasing the time you spend in debt.
Overlooking prepayment penalties. Check your current mortgage documents and ask whether any charges apply when the existing loan is paid off.
Taking too much cash out. Cash-out refinancing increases the debt secured by your home and can reduce the equity available for future needs.
Failing to compare written offers. Obtain Loan Estimates from multiple lenders and compare equivalent loan structures.
Frequently Asked Questions
Who is the best mortgage refinance lender in 2026?
There is no single best lender for every homeowner. NerdWallet named Truist its top refinance lender in its 2026 rankings, while Alliant and State Employees’ Credit Union also received high marks. Compare personalized offers to determine which lender fits your needs.
How can I find the lowest mortgage refinance rate?
Request quotes from several banks, credit unions, and online lenders on the same day when possible. Compare APR, points, closing costs, rate-lock terms, and the total cost of the loan—not just the advertised interest rate.
What credit score do I need to refinance a mortgage?
There is no universal minimum. Requirements vary according to the lender, loan type, equity, and other financial factors. A stronger credit profile may help you qualify for more competitive terms, but you should check the requirements of each program.
How much does refinancing a mortgage cost?
Costs depend on the loan, lender, property, and location. Expenses may include origination, appraisal, title, recording, and other closing charges. Request a Loan Estimate to see the expected costs for your situation.
Can I refinance without closing costs?
Some lenders offer no-closing-cost refinancing. These offers may cover certain expenses in exchange for a higher interest rate or add costs to the loan balance. Check the terms carefully because the expenses may be shifted rather than eliminated.
Is refinancing worth it if I plan to move soon?
It may not be. If your expected monthly savings will not recover the refinancing costs before you move, refinancing could leave you financially worse off. Calculate your break-even period first.
Can I refinance to get cash from my home?
A cash-out refinance may allow eligible homeowners to borrow against their equity. Approval depends on factors such as property value, remaining mortgage balance, credit, income, and lender rules. Remember that your home secures the new debt.
Final Thoughts
Finding the best mortgage refinance lender in 2026 means comparing the full cost and structure of each loan. Truist, Rocket Mortgage, Alliant Credit Union, State Employees’ Credit Union, Navy Federal Credit Union, and loanDepot are possible starting points, depending on eligibility and refinancing goals.
Before choosing a lender, obtain multiple written quotes, compare APR and closing costs, calculate your break-even period, and confirm that the new loan supports your long-term financial plans. A lower monthly payment can be helpful, but the best refinance is the one that makes sense for your overall finances.
Disclaimer: This article is for informational and educational purposes only and is not financial, tax, or legal advice. Lender availability, eligibility criteria, interest rates, and fees may change. Verify all details directly with the lender and consider consulting a qualified financial professional before refinancing.