Managing money has become increasingly complex as people navigate investments, retirement planning, taxes, debt, and changing economic conditions. A financial advisor can help individuals and businesses make informed financial decisions, develop long-term plans, and work toward their financial goals.
Whether you want to grow your savings, prepare for retirement, invest in the stock market, or manage business finances, understanding how financial advisors work can help you decide whether professional guidance is right for you.
In this guide, we explain what financial advisors do, the different types available, their potential benefits, how they charge fees, and how to choose a suitable advisor in 2026.
What Is a Financial Advisor?
A financial advisor is a professional who provides guidance on financial matters. Depending on their qualifications and services, they may help clients with investments, retirement planning, budgeting, tax-efficient strategies, insurance needs, and wealth management.
Some advisors work independently, while others are employed by banks, investment firms, financial planning companies, or wealth management organizations.
The services offered can vary significantly. An investment advisor may focus primarily on investment portfolios, while a financial planner may consider a client's broader financial situation, including income, expenses, savings, debts, and future goals.
Not every person who calls themselves a financial advisor has the same qualifications or legal responsibilities. It is important to check professional credentials, relevant registrations, experience, and the way the advisor is compensated.
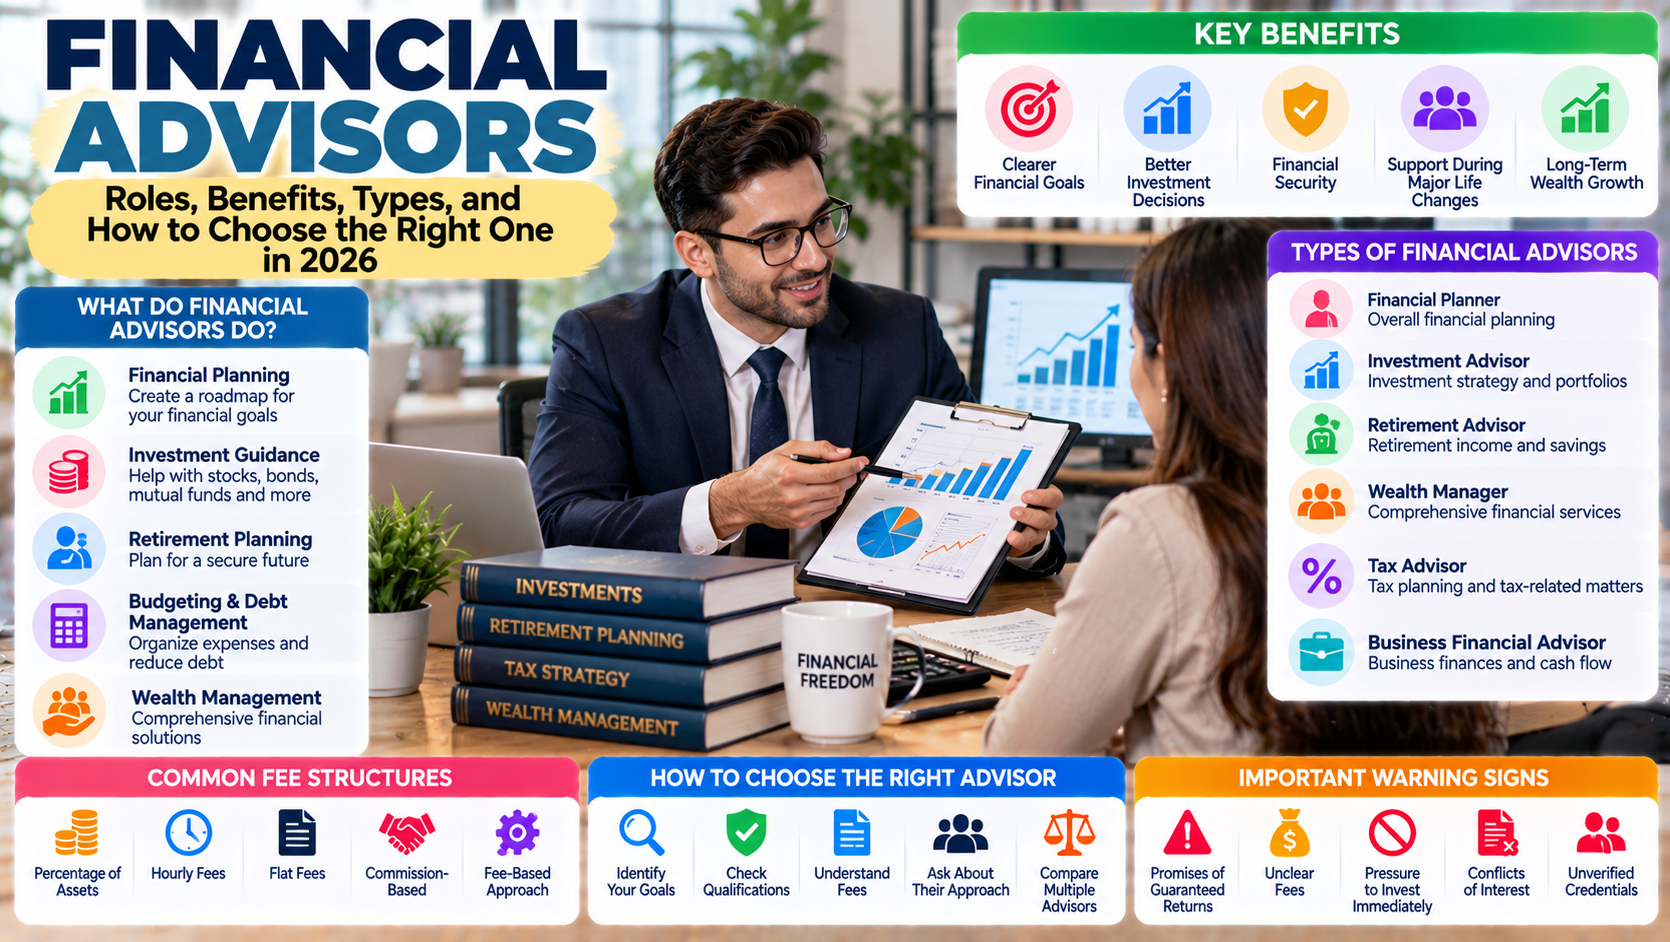
What Does a Financial Advisor Do?
Financial advisors provide different services depending on their expertise and the needs of their clients.
1. Financial Planning
A financial advisor can help clients understand their current financial position and create a plan for future goals. This may include building savings, managing debt, preparing for major purchases, and planning for long-term expenses.
A financial plan can also help people identify gaps between their current financial habits and their future objectives.
2. Investment Guidance
Some financial advisors help clients understand investment options such as stocks, bonds, mutual funds, exchange-traded funds, and other financial products.
They may assess investment goals, time horizons, and tolerance for risk before recommending an appropriate strategy.
Investments can lose value, and no advisor can guarantee a profit or eliminate all financial risk.
3. Retirement Planning
Retirement planning involves estimating future expenses, reviewing savings, and considering potential income sources after employment ends.
An advisor may help clients evaluate retirement accounts, savings strategies, withdrawal plans, and the financial implications of retiring at different ages.
4. Budgeting and Debt Management
Financial advisors may help clients organize monthly expenses, build emergency savings, and develop a realistic debt repayment strategy.
This can be particularly useful for people managing multiple loans, planning a major purchase, or trying to improve their financial stability.
5. Wealth Management
Wealth management is a broader service that may combine investment advice, financial planning, estate considerations, and coordination with tax or legal professionals.
These services are often designed for clients with more complex financial needs, although the exact requirements vary by firm.
Types of Financial Advisors
Different financial professionals specialize in different areas. Understanding these distinctions can help you choose the right service.
Type of advisor | Main focus | Suitable for |
|---|---|---|
Financial planner | Overall financial goals and planning | Individuals and families |
Investment advisor | Investment strategy and portfolio management | People seeking investment guidance |
Retirement advisor | Retirement income and savings planning | People preparing for retirement |
Wealth manager | Broader financial and investment needs | Clients with complex finances |
Tax advisor | Tax planning and tax-related matters | Individuals and businesses with tax questions |
Business financial advisor | Business finances, cash flow, and financial strategy | Business owners and entrepreneurs |
Some professionals provide several of these services. Always verify whether their qualifications and legal permissions cover the advice you need.
Benefits of Working With a Financial Advisor
Hiring a financial advisor may offer several advantages, depending on your circumstances.
1. Clearer Financial Goals
A financial advisor can help turn broad goals into a practical plan. Instead of simply hoping to save more money, you can establish a savings target, timeline, and strategy for reaching it.
2. Better Understanding of Investment Risk
Financial advisors can explain how different investments work, including their potential returns, costs, liquidity, and risks.
This guidance may help clients make more informed decisions rather than relying entirely on speculation or short-term market movements.
3. A More Organized Financial Plan
A structured plan can bring budgeting, savings, insurance, debt, and investments into a single framework. This may make it easier to identify priorities and track progress.
4. Support During Major Life Changes
Events such as marriage, starting a business, buying a home, receiving an inheritance, or approaching retirement can create new financial challenges.
An advisor may help evaluate available options and understand their potential financial consequences.
5. Accountability and Ongoing Reviews
Some advisors provide regular meetings to review financial goals, spending, investments, and changes in personal circumstances.
However, the quality of advice depends on the professional's competence, incentives, communication, and understanding of the client's needs.
How Much Does a Financial Advisor Cost?
Financial advisor fees depend on the country, the type of service, the advisor's experience, and the complexity of the client's finances.
Common fee structures include:
Percentage of assets under management: The advisor charges a percentage of the investments they manage.
Hourly fees: The client pays for the time spent providing advice.
Flat fees: A fixed amount is charged for a defined service or financial plan.
Commission-based compensation: The advisor receives commissions from certain financial products or transactions.
Fee-based arrangements: The advisor may charge direct fees while also receiving certain commissions, depending on the arrangement.
Before hiring an advisor, request a clear explanation of all fees, including investment expenses, transaction costs, and any compensation received from product providers.
A lower advertised fee does not necessarily mean a service will cost less overall.
How to Choose the Right Financial Advisor
Choosing a financial advisor requires more than comparing advertisements or relying on recommendations from friends.
Step 1: Identify Your Financial Goals
Decide what you need help with. You may require a retirement plan, investment guidance, debt management, business financial planning, or a comprehensive financial review.
Knowing your goals makes it easier to find an advisor with relevant expertise.
Step 2: Check Qualifications and Registration
Review the advisor's education, professional certifications, experience, and regulatory registration where applicable.
In the United States, for example, you can use resources from the Securities and Exchange Commission and FINRA to research certain financial professionals and firms. Other countries have their own regulatory authorities and verification systems.
Step 3: Understand Their Compensation
Ask how the advisor earns money and whether they receive commissions or other financial incentives for recommending specific products.
Request the full fee schedule in writing before signing an agreement.
Step 4: Ask About Their Approach
A suitable advisor should be willing to explain their recommendations in clear language, discuss risks, and answer questions.
Ask how they assess your financial circumstances, how often they review plans, and what happens if your goals or income change.
Step 5: Review Their Professional Background
Look for relevant disciplinary history, complaints, conflicts of interest, and any restrictions on professional activities through the appropriate regulatory bodies.
Do not assume that a polished website or a large social media following proves that an advisor is trustworthy.
Step 6: Compare More Than One Advisor
Speaking with several professionals can help you compare their services, fees, communication styles, and investment approaches before making a decision.
Financial Advisor vs. Managing Your Finances Yourself
Not everyone needs to hire a financial advisor. Some people can manage straightforward financial situations independently, while others may benefit from professional guidance.
Factor | Financial advisor | Self-directed financial management |
|---|---|---|
Guidance | Professional support within the advisor's expertise | Relies on personal research and knowledge |
Cost | May involve ongoing or one-time fees | May reduce advisory fees, but other costs can apply |
Control | Depends on the agreed service and arrangement | The individual makes the decisions |
Time commitment | Some research and administration may be handled by the advisor | Requires personal time for research and monitoring |
Complexity | Can help with complicated financial needs | May be challenging when finances become complex |
The right choice depends on your financial knowledge, available time, goals, and comfort with making financial decisions.
Warning Signs to Watch For
Be cautious when evaluating financial advisors or anyone offering financial guidance.
Potential warning signs include:
Promises of guaranteed high investment returns.
Pressure to transfer money immediately.
Unclear fees or reluctance to explain compensation.
Recommendations that do not match your goals or risk tolerance.
Requests to send money to an unrelated personal account.
Claims of special investment opportunities that cannot be independently verified.
Refusal to provide relevant credentials or regulatory information.
Never rely solely on testimonials, screenshots of profits, or social media claims. Verify the professional and any investment opportunity independently.
Financial Advisors for Small Businesses
Small business owners may use financial advisors to evaluate cash flow, plan budgets, assess financing options, and prepare for expansion.
A business-focused advisor may help with financial forecasting, cost management, funding decisions, and identifying financial risks.
However, business financial advice is not necessarily the same as accounting, auditing, legal advice, or tax preparation. Business owners should confirm which services the advisor is qualified to provide and work with other appropriate professionals when necessary.
Frequently Asked Questions
What is the main purpose of a financial advisor?
A financial advisor helps clients make informed decisions about financial goals, investments, savings, retirement, or other financial matters, depending on the advisor's qualifications and services.
Is hiring a financial advisor worth it?
It may be worthwhile if you have complex finances, need specialized guidance, or want help developing a financial plan. The value depends on the quality of the advice, the cost, and your individual needs.
Can a financial advisor guarantee investment returns?
No. Legitimate investment advice cannot guarantee that an investment will make a profit or avoid losses. Be cautious of anyone promising guaranteed high returns from risky investments.
How do financial advisors get paid?
They may charge hourly fees, flat fees, a percentage of assets under management, commissions, or a combination of these arrangements. Always ask for written details.
Do beginners need a financial advisor?
Not necessarily. Beginners can start by learning about budgeting, emergency savings, debt management, and basic investment principles. Professional advice may become useful when financial decisions become more complex.
How can I verify a financial advisor?
Check the advisor's credentials, registration, disciplinary history, employer or firm, and compensation arrangements using the relevant official regulatory resources in your country.
Final Thoughts
Financial advisors can help individuals and businesses organize their finances, evaluate investment choices, and plan for future goals. However, the right professional depends on your specific needs, financial circumstances, and the type of guidance required.
Before hiring an advisor, verify their qualifications, understand their fees, investigate potential conflicts of interest, and make sure their recommendations align with your goals and tolerance for risk.
A well-informed financial decision starts with understanding your options, asking questions, and avoiding promises that sound too good to be true.
Disclaimer: This article is for educational purposes only and does not constitute personalized financial, investment, tax, or legal advice. Consider consulting an appropriately qualified professional before making important financial decisions.